Big Pharma’s Overlooked Drugs Can Become Billion-Dollar Businesses
 David Sacks
 David Friedberg
 Jason Calacanis
 Chamath PalihapitiyaMartin ShkreliAll-In PodcastMonday, October 12, 20268 min read
Martin Shkreli argues that a technology’s technical breakthrough does not make it a sound investment: quantum computing may excel at a narrow set of problems, he says, without offering a viable business case. In a conversation with the Besties, he also describes pharmaceutical opportunity as finding drugs large companies have failed to develop well, while disputing claims that AI will soon transform drug discovery. Looking back on prison, Shkreli says his fixation on being a great trader obscured other paths and relationships that mattered more.
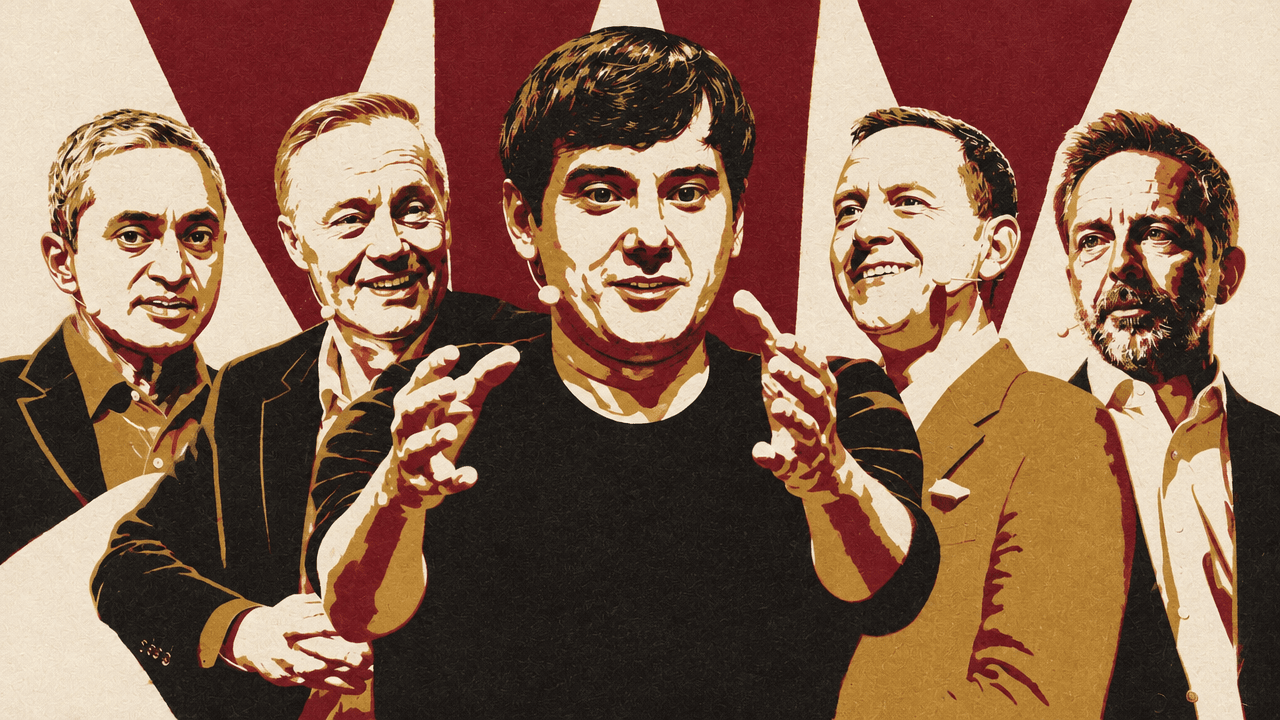
The Daraprim price increase made Shkreli a public symbol of profit maximization
The opening account of Martin Shkreli’s career centered on Daraprim’s price: from $13.50 to $750 a pill. Shkreli said, “You can be prosecuted for not maximizing profit,” and described doing everything in his power to make as much money as possible. He added that he was happy to be seen as the enemy if that fulfilled a need in someone else’s life.
The opening also recalled Shkreli’s purchase of the only copy of a Wu-Tang Clan album for $2 million. Asked about the record, he said, “It’s not a good record.” He also offered a broader principle: “Ego is the fountainhead of all progress.”
He began working at Jim Cramer’s hedge fund at 16. Shkreli described Cramer as a skilled trader whose approach involved buying and selling constantly, and said he later worked at a Tiger Cub fund before starting his own. Over time, he concluded that he was better at entrepreneurship and private equity than at trading. He said he had difficulty admitting that he might not be the best hedge-fund manager in the world, even though he believed he was a strong entrepreneur.
That account came during a discussion of Sam Bankman-Fried, whom Shkreli said he had advised. David Sacks asked whether the qualities that made Bankman-Fried an unconventional thinker and investor also contributed to his troubles. Shkreli said intellectual giftedness could become an “albatross”: people who grow up believing they are exceptional may feel compelled to live up to that identity. He cited Bankman-Fried, Elizabeth Holmes and hedge-fund manager Raj Rajaratnam, then connected the pattern to his own experience.
I had a hard time admitting I was not the best hedge fund manager in the world, but I was a wonderful entrepreneur. That simple refusal to admit that put me in prison.
His drug-development thesis began with finding what a company had overlooked
Shkreli’s account of moving from trading into pharmaceuticals was not simply a story about buying a drug and raising its price. He said he saw an inefficient market in which large companies sometimes held assets they did not know how to develop or commercialize. His work, as he described it, was to find those assets, assess the research and identify a development path that could make a drug useful in a different market.
He said he bought a drug from Bristol-Myers for $2 million, and that “that same company” is now worth $6 billion. He also described pharmaceutical companies as sometimes willing to sell a drug for a small sum even when, in his view, it might be worth much more to another developer. The gap was not automatically an opportunity: his teams needed to determine which assets had promise and what to do with them.
Shkreli said that vetting began with reading scientific papers and patents, and with building relationships at universities and small and large drug companies. He called that work business development. Finding people who could evaluate the assets was a constraint, and the volume of research made the process difficult. In 2015, he started a small natural-language-processing company to help review medical literature. The team tried to read some 40 million papers; Shkreli said it was a difficult task for humans to take on.
One example of a development decision was sparsentan, a drug Shkreli said he named. Bristol-Myers had developed it for hypertension, which he characterized as a crowded, sleepy market. His team redirected it toward focal segmental glomerulosclerosis, or FSGS, a kidney disease for which he said no drug had previously been approved. He said the drug later received FDA approval and that about 30,000 people with FSGS now had a drug. He presented this as an example of work that could produce both a financial return and a treatment for people who had lacked one.
Quantum’s narrow advantage is not, in his view, a business case
Shkreli’s investment skepticism follows a distinction between a striking technical result and a business that can make money. He said his wife, Chelsea, studied at MIT and taught quantum computing with Scott Aaronson, whom he called a leading figure in the field. After she spent hours explaining the subject to him, he concluded that quantum computing was often mistaken for a faster version of conventional computing.
His account of the field’s central achievement focused on Peter Shor’s algorithm. Shkreli said quantum computers could solve integer factorization and the elliptic-curve discrete-log problem in polynomial rather than exponential time. He called that a remarkable “magic trick,” especially from a technical perspective. His objection was that this advantage did not translate into faster performance across ordinary computing tasks. For a business not concerned with those particular problems, he argued, there was little reason to expect quantum machines to replace conventional ones.
He used sorting as a test. Shkreli said quantum advocates had told him a quantum computer could sort a deck of cards faster, a claim he disputed. He described current machines as running at hundreds or thousands of hertz, rather than the gigahertz speeds familiar in conventional computing, and as limited in their ability to do ordinary tasks in parallel. He also said there was no quantum RAM, which in his view constrained the size of problems that could be put on the machines.
Chamath Palihapitiya put forward the counterargument: the field might simply be at an early stage, before mature gates, operating systems and software tools exist. Shkreli accepted that quantum computing could advance. But he compared the investment case to betting on earlier technologies such as punch cards, vacuum tubes, mercury delay lines and core memory—systems that had once mattered commercially but later disappeared. He said companies including Google, IBM and Microsoft spent hundreds of millions of dollars a year on quantum research because something useful might emerge someday; he did not consider that a strong business proposition.
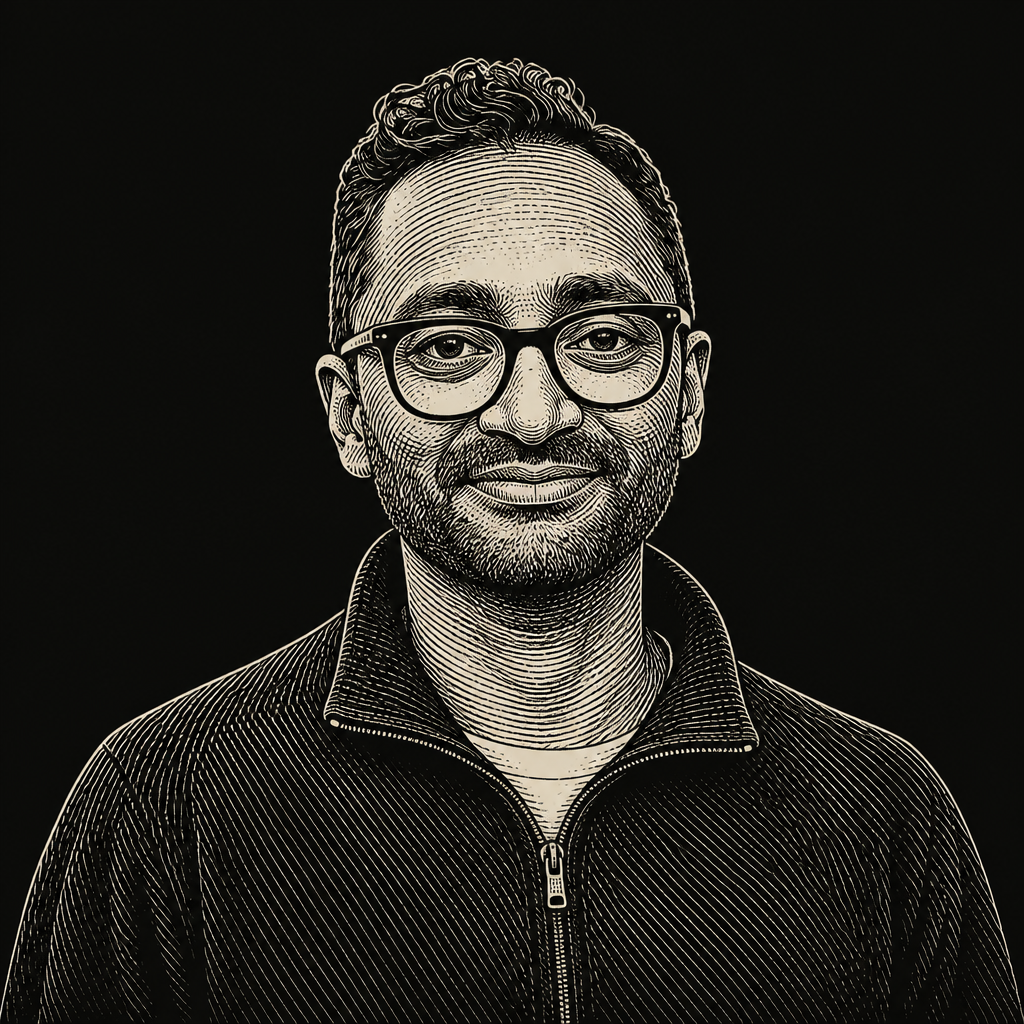
Shkreli said he and Chelsea had tried every quantum computer in the world and could not get one to multiply 300 by 200. He also disclosed that he had shorted quantum companies and lost millions of dollars. His account distinguishes having a thesis about a technology from making money from a position: even while arguing that the commercial case was weak, he acknowledged that timing the market was difficult.
His attention had also moved to analog optical computing. After seeing a Microsoft paper, he said he was investigating the possibility that matrix multiplication could happen in light almost instantaneously. He noted that GPUs spend most of their time doing matrix multiplication and named Neurophos, Opticore and Lumai as startups working on photonic matrix-multiplication cores. He also cautioned that this was not the whole problem, citing storage and nonlinear operations as unresolved details.
On the broader semiconductor market, Shkreli said he was long semiconductors while expecting today’s chips eventually to be superseded. He saw a tension between more efficient models, which could reduce compute demand for a given task, and cheaper compute, which could open up new uses. He invoked Jevons paradox but said he did not know whether demand would grow enough to absorb a millionfold improvement in efficiency. As he put it, an investor in 2000 might have believed Yahoo and Cisco were obvious long-term winners. Technological change, in his telling, does not settle the question of which companies will benefit.
He expects AI to expand demand, but disputes the claim that it will soon discover drugs
Shkreli argued that the market for AI should not be measured only by how many knowledge workers it could replace. In his view, demand for intelligence and work has no clear upper bound. Companies might use AI to make products, investigate decisions or operate businesses that would otherwise require larger teams.
He offered a hypothetical: McDonald’s could spend $10 billion on compute to ask what sandwich it should launch, if the intelligence produced were valuable enough. He also imagined AI providers building businesses in areas such as pharmaceuticals, motors and aviation—potentially creating what he called an entire S&P 500 within OpenAI, Anthropic or another company. He framed these as possibilities, while allowing that more tokens might eventually stop producing better answers.
For the market’s structure, he compared AI partly to the internet. Consumers and businesses, he said, may capture much of the benefit through access to cheap or free intelligence, while infrastructure providers earn some of the value without necessarily becoming the main winners. The investment challenge is to identify who can earn unusually high returns and how long those returns will last.
Shkreli named Meta as a company he thought could benefit, pointing to its distribution, its product capabilities and its Muse offering. He said he believed AI was still at an early stage, and that today’s chatbots might later look like early calculators. He also said he had exposure to OpenAI and viewed Sam Altman’s move into hardware as strategically strong: a leading model matters, but delivering it to users may matter more.
His optimism about the size of the opportunity did not extend to every claim made on AI’s behalf. Shkreli said AI would not help drug discovery in a meaningful way and rejected predictions that it would quickly cure diseases. He said he had built a Cray cluster to analyze drugs and now used GPUs, but did not see much AI could add to the process. He argued that developing a drug remained difficult despite the long-standing use of computers in the field. He said he did not expect an AI-relevant drug in the next ten years.
The discussion of AI safety brought a separate disagreement. Shkreli accused Dario of fearmongering and objected to Anthropic’s origins, comparing the departure of OpenAI employees to taking the idea for a business and starting a competing company. Palihapitiya pushed back, distinguishing retained knowledge from the theft of physical documents and saying he did not know what had happened.
Shkreli also criticized effective altruism and described effective accelerationism as a counter-movement favoring faster development. He said AI was important software but not an existential threat that required stopping progress. David Friedberg later connected unconventional thinking with the possibility of difficulty following conventional rules. In response, Shkreli’s point about giftedness was that intelligence in one area did not guarantee good judgment in another—a distinction he also applied to his own career.
Prison shifted his focus from status to the relationships people share
Asked what prison had changed, Shkreli said it had helped him see how much psychology shaped his decisions. He had not understood how frightened he was of losing the identity of a great trader. That fixation, he said, was unnecessary: he could have been a long-term investor, entrepreneur, scientist or father. The problem was making one role the measure of his worth.
His description of prison centered on ordinary attachments. People from different backgrounds, he said, shared concerns about whether friends had stayed in touch, missing someone, and wanting to be a good parent. He said it was refreshing to be reminded that, whatever heights people achieve, they share those needs.