Jensen Huang’s Exit Raises Questions About Nvidia’s Governance and China Ties
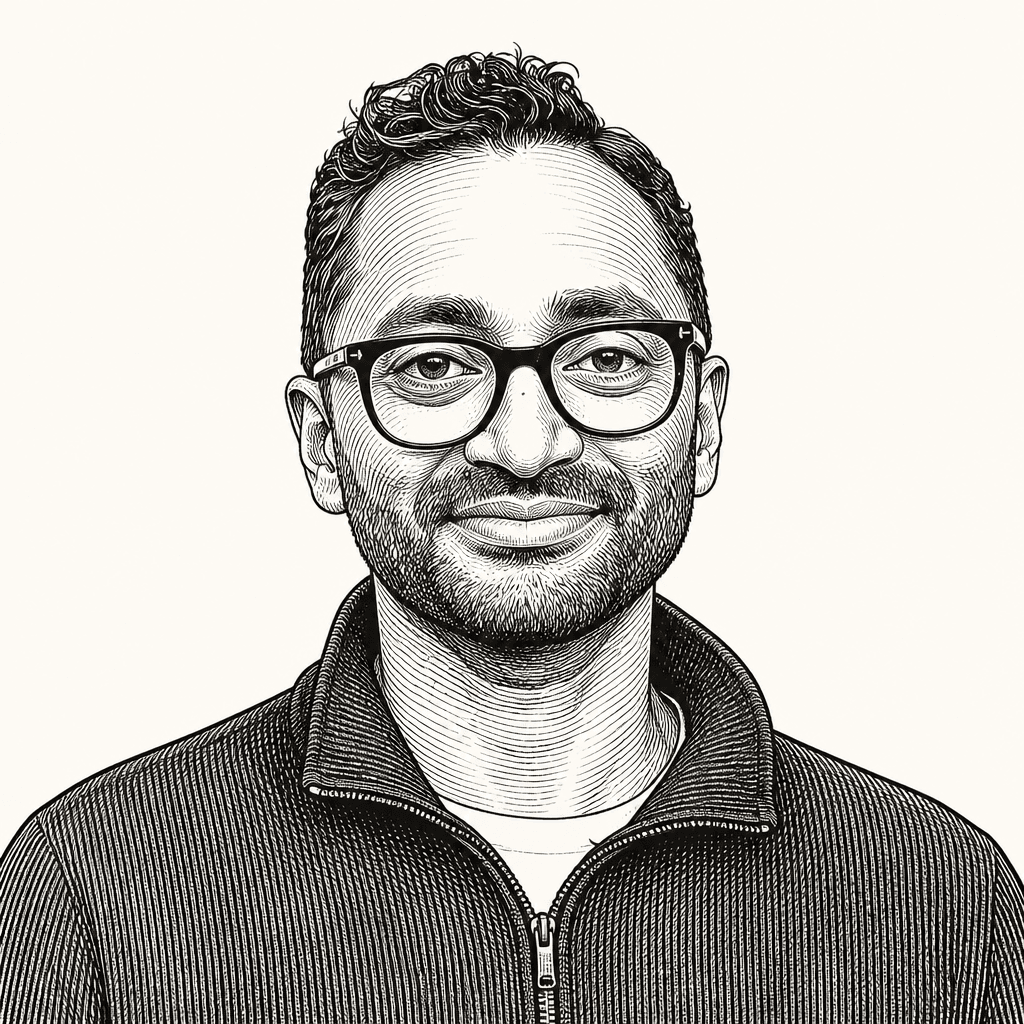 Chamath Palihapitiya
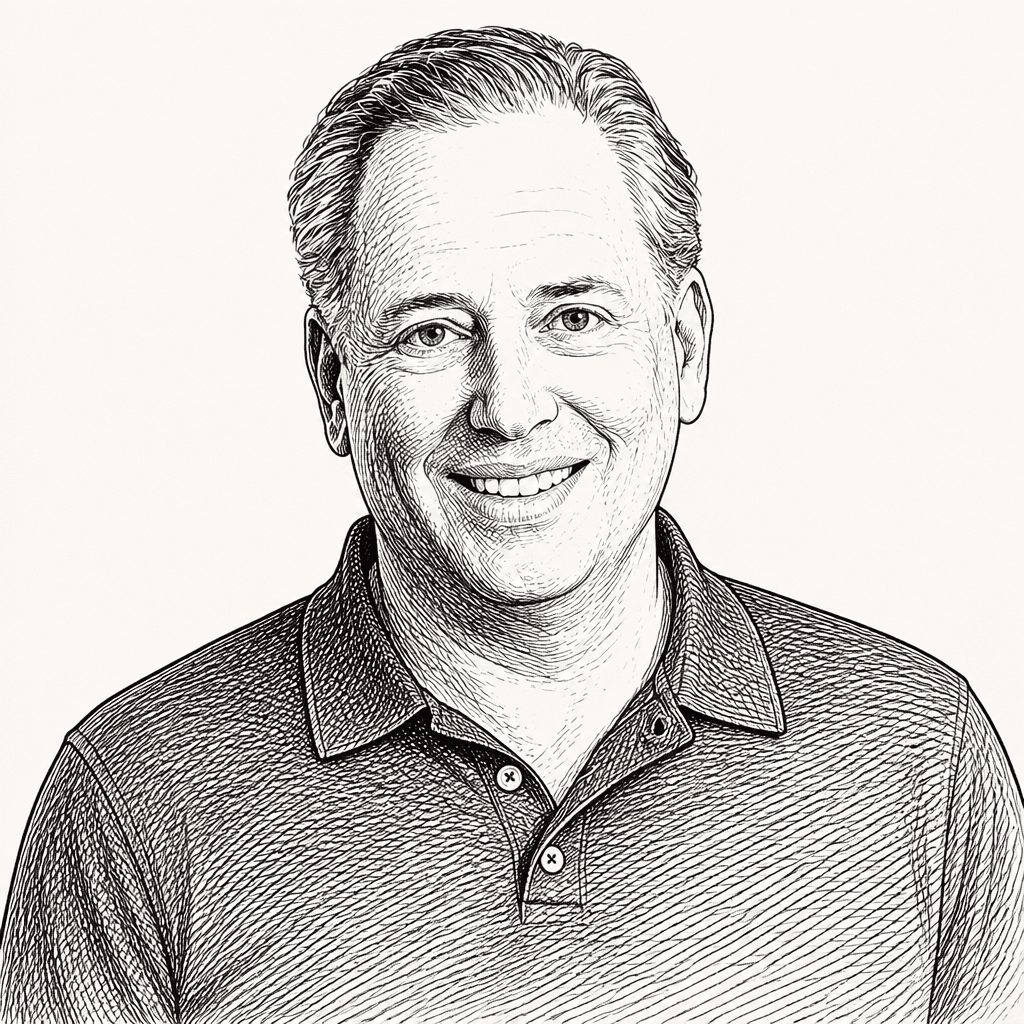 David Sacks
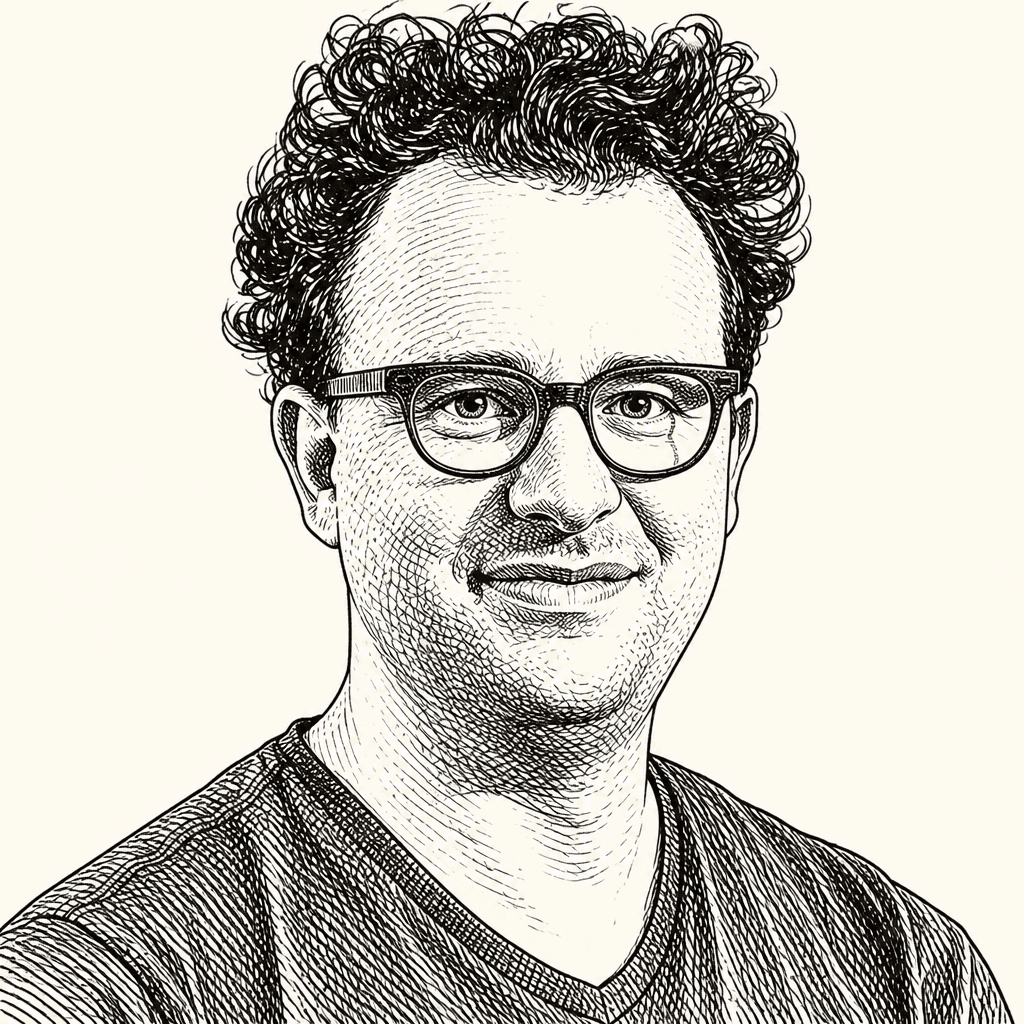 Dario Amodei
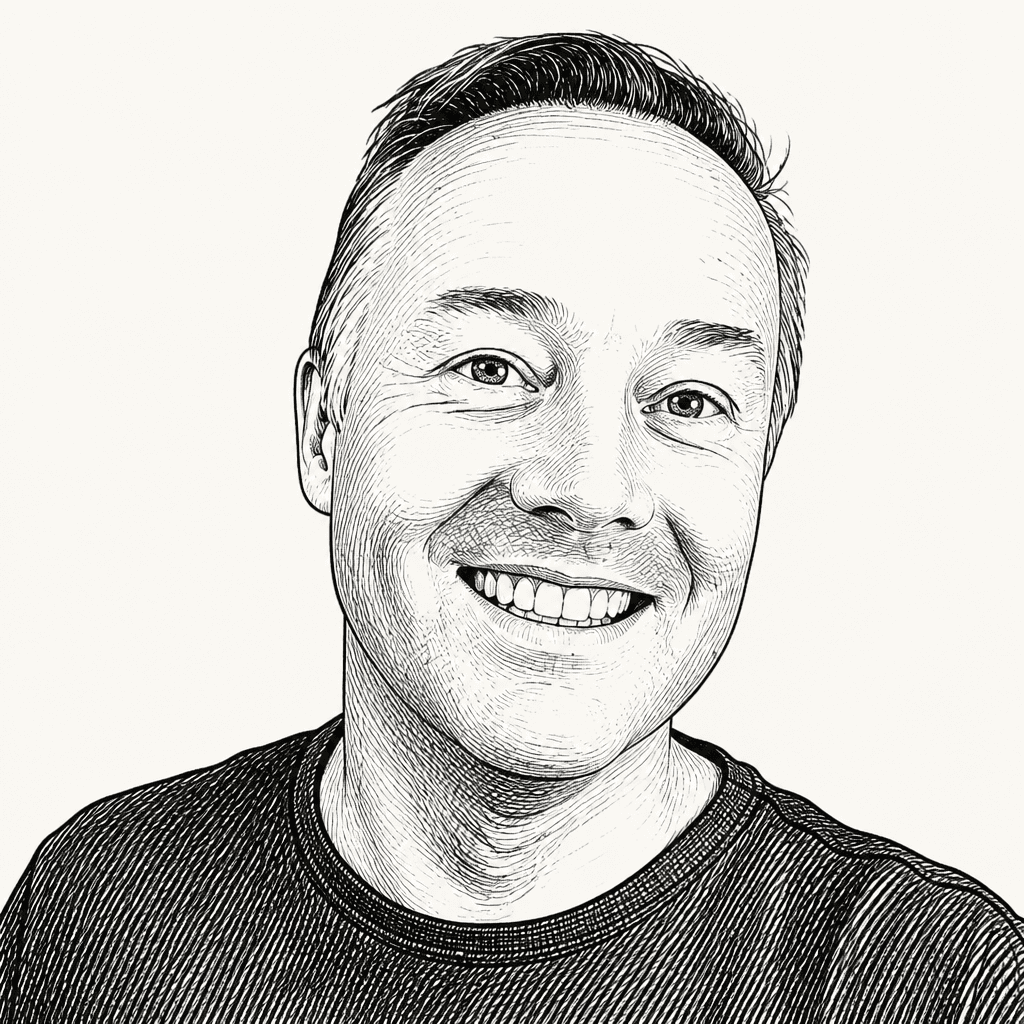 Jason Calacanis
 David FriedbergAll-In PodcastSaturday, November 14, 202615 min read
Nvidia announced that Jensen Huang had resigned after 33 years as chief executive, but the panelists said the public record did not establish whether he left voluntarily or was forced out. David Sacks argued that allegations linking Huang to a Chinese intelligence asset and questions about possible chip diversion warrant investigation, while also calling for scrutiny of the leak of classified material. The panel offered competing theories about the timing and consequences of the departure, with no settled account of the board’s reasons.
The record supports two investigations, but not yet a settled account of Jensen Huang’s exit
When the panel recorded on November 12, Nvidia had announced that Jensen Huang had resigned after 33 years as chief executive. Chief Financial Officer Colette Kress was named interim CEO, and Harvey C. Jones was appointed the board’s first chair. The board was searching for a permanent successor, with earnings due the following Tuesday. Jason Calacanis said Nvidia’s stock had fallen 15% in a week, a loss of hundreds of billions of dollars in market value.
The transition card shown during the discussion said “Jensen Huang Resigns.” But the panel and headlines it displayed also described him as “ousted” or “fired.” The source establishes the resignation and interim appointment; it does not establish whether Huang left voluntarily or was removed by the board.
The immediate public trigger was a November 6 New York Times report describing Alice Huang, an executive at Singapore-based data-center company Megaspeed, as a Chinese intelligence asset who had developed a close relationship with Jensen Huang. The two are not related. Megaspeed builds data centers and rents computing capacity, including to Chinese companies such as Alibaba. Calacanis said reporting connected the relationship to more than $7 billion in Nvidia chip sales to Chinese companies since 2023.
The Times report drew on a leaked intelligence memo. A story about Alice Huang’s relationship with Jensen had appeared in the paper in October 2025, and the panel noted that the connection had therefore been reported more than a year before the resignation. On November 8, Jensen reportedly emailed Nvidia employees acknowledging an affair and saying the board would investigate. On November 11, the Times reported a second relationship, with an Nvidia executive who reported to him. Calacanis mentioned reports of a possible third relationship, then asked the panel to focus on the resignation and the intelligence allegations.
Those reports and allegations do not resolve what happened. David Sacks separated the matter into two questions: what Alice Huang and Megaspeed did, including whether chips were diverted to China, and how classified intelligence about the case reached the press. Sacks said the first question warranted a full investigation. If Nvidia or Jensen knowingly enabled smuggling or broke the law, he said, there should be consequences. He also argued that the leak of classified material should be investigated.
Sacks’s questions about the national-security case were specific: Who leaked the memo, and why? Why was Jensen not given a defensive briefing? What classified secrets did he supposedly know or disclose? And was Alice Huang actually a Chinese spy? He said the New York Times’s description of sources as “people briefed on the matter” did not establish that a senior political official was responsible; the sources could have been low-level or career officials. Calacanis pointed out that Marco Rubio had led the investigation and briefed President Trump, but Sacks cautioned against treating that as evidence Rubio was the leaker.
The question of what Jensen could have disclosed mattered to Sacks because he was a private-sector executive, not a government official known to have access to classified material. Sacks argued that acquiring the design of a chip would require access to design files, not merely a commercially available chip. He suggested that an engineer with access to those files, or a cyberattack, would be a more plausible route to obtaining them than a personal relationship. Calacanis interjected that chips can help produce advanced AI models; Sacks replied that this did not answer his question about what specific secrets Jensen was alleged to have compromised.
A Politico report shown during the discussion added uncertainty about Alice Huang’s status. After a classified briefing, Representative Jim Himes, the incoming chair of the House Intelligence Committee, reportedly said he was unsure whether she was a spy or a “useful idiot.” The report also said intelligence leaders did not know whether the FBI had investigated her after concerns arose about her relationship with Jensen. For Sacks, the distinction was important: someone might be exploited by a foreign government without being an agent of that government.
He also questioned why Jensen had not received a warning. Sacks compared the case with former congressman Eric Swalwell, who, he said, received a defensive briefing after his relationship with suspected Chinese spy Christine Fang became public and remained in Congress and on the House Intelligence Committee. The comparison was an argument about different responses, not evidence that the cases were equivalent. If officials believed Jensen was exposed to a suspected intelligence asset, Sacks asked, why not warn him and let him cut off contact?
The panel offered competing explanations for the timing, not a settled account of who caused the resignation. Chamath Palihapitiya asked why the information had been released when it was. David Friedberg noted that the affair and spy stories surfaced close together. Calacanis speculated that China hawks who had lost a debate over chip sales might be trying to change export policy, and raised the possibility of conflict within the White House or a political leak meant to create chaos.
The board’s decision could also have involved company governance rather than a criminal finding. Friedberg said public-company executives make compliance attestations and disclosures about conflicts of interest, including relationships with subordinates or business partners. If Jensen had failed to disclose a relationship or made an inaccurate attestation, Friedberg suggested, the board could face a problem even if no criminal charge followed. Palihapitiya described the practical pressures: auditor questions, conflict disclosures and covenants tied to directors’ and officers’ insurance. Neither speaker claimed to know the board’s actual rationale.
That possibility complicates the question of whether Jensen could return. Friedberg said shareholders could decide whether a breach of company rules justified keeping him out, if he had not broken the law. Calacanis said he hoped Jensen would be exonerated and return as CEO or chair. Sacks said he had no prior personal relationship with Jensen, whom he first met at the White House, and that his view rested on Jensen’s value as a founder rather than personal loyalty.
Palihapitiya expected shareholder litigation, pointing to the large fall in Nvidia’s market value and to unresolved questions about company disclosures. He said Nvidia’s public communications had shifted from denying a relationship to acknowledging one, and argued that civil claims could focus on the resulting harm even if investigators found no criminal conduct. Those claims and their potential value remained prospective.
Nvidia’s risk is losing momentum—and the capital that keeps the AI buildout moving
The panel’s most consequential market concern was not that Nvidia’s competitors would automatically inherit its business. It was that the AI industry could lose speed if Nvidia’s product cycle and investment activity slowed at the same time.
Sacks described Nvidia’s advantage as an ability to keep producing more powerful chips, not simply possession of a particular generation. He cited the progression from Ampere to Hopper to Blackwell and then Vera Rubin, arguing that rapid iteration is what keeps the United States at the frontier. If Nvidia lost one or two development cycles amid leadership turmoil, he said, the effect could extend beyond the company. A successor might preserve the existing business but fail to sustain the pace that had made it strategically important.
Palihapitiya agreed that Nvidia could slow, but resisted the idea that the resulting demand would promptly move to another supplier. Rival companies still need to make their chips work at scale, secure manufacturing and high-bandwidth-memory capacity, and build networking and software systems. They cannot simply will a million-GPU training run into existence, he said. A weaker Nvidia would not automatically produce a stronger AMD, Google, Cerebras or Etched.
Huawei illustrated why a slowdown might still matter strategically. Sacks said Huawei had moved from its Ascend chips to a Cloud Matrix system that networks 384 chips together. Nvidia’s NVL72 system, by contrast, networks 72 chips; Sacks said it performed better than Huawei’s larger system. Huawei was nevertheless getting closer by combining less powerful chips and using more energy to achieve system-level performance. If Nvidia were substantially disrupted for two or three years, Sacks argued, Huawei could close more of the gap.
The panel distinguished that technological risk from the economic effects of reduced investment. Friedberg described Nvidia as a source of capital and guarantees for startups, data centers and other AI infrastructure, much of it directed by Jensen. Palihapitiya called this the “Bank of Nvidia”: an investment function whose future was unclear without its founder. The question was whether it would pause, resume under a new CEO, or become more cautious.
In Palihapitiya’s account, Jensen had a broad view of the industry and the authority to make investments and acquisitions quickly. A more conventional chief executive might rely on committees and extended diligence, slowing decisions even without ending the investment program. Friedberg added that Jensen knew the people and the market personally. The risk, as they described it, was not only a change in Nvidia’s competitive position but a slower flow of capital through the broader AI economy.
Friedberg connected that risk to opposition to data-center construction. He argued that reduced Nvidia financing, combined with local campaigns and legislation that slow data-center development, could reduce the velocity of investment that drives model and chip advances. Calacanis and Friedberg raised possible geopolitical or political motives behind some opposition. Palihapitiya cautioned that the motive need not be foreign: someone who expected political advantage from a recession, or who opposed AI on principle, might also favor a slowdown. The panel did not show that these efforts were coordinated.
Palihapitiya estimated that the possibility of losing 50 to 150 basis points of growth should now be taken seriously. He linked that risk to anticipated political headwinds for data centers and to Nvidia’s role as a financing anchor. This was a forecast about possible economic effects, not a calculation of losses already caused by the CEO change.
The contrast with Apple’s succession after Steve Jobs helped clarify the stakes. Calacanis said Tim Cook had delivered substantial shareholder appreciation but largely extended Apple’s existing product lines. Sacks argued that Nvidia could not simply milk its roadmap in the same way: chips are improving rapidly, and a company that loses pace can fall behind. The analogy was therefore less about whether a professional manager could operate Nvidia than whether one could maintain its rate of technical and commercial iteration.
Tracking chips could shift from corporate compliance to government control
The export-control dispute connects Nvidia’s China sales to a broader question: who would operate any system for monitoring or disabling advanced chips?
Palihapitiya said current export-control arrangements require companies to provide telemetry and remote shutdown capability for chips sold under restrictions. In his description, firms such as Amazon, Microsoft and Google carry responsibility through the regulatory framework. He warned that the current controversy could create an opening for legislation that gives the government direct control over tracking or shutdown systems.
Calacanis raised the prospect of chips, computers and data centers being connected to a central state system. Palihapitiya argued that companies might not merely accept such requirements but proactively design controls into products to satisfy the government. Sacks acknowledged the civil-liberties concern. The panel’s disagreement was not over whether tracking was technically possible, but over who should hold authority and what that authority could become.
Friedberg referred to the bipartisan CHIPS Security Act and described a distinction between corporate and government enforcement. In one version, Nvidia would track chips, reinitialize them if resold, and face consequences if they appeared in China through an intermediary. In another, a government body would control the tracking mechanism. Friedberg said the underlying technology was straightforward, comparing it to consumer devices that can be recovered or disabled. He identified privacy and civil liberties, rather than technical feasibility, as the central concern.
Palihapitiya pointed to a statement by Representative John Moolenaar, shown during the discussion. Moolenaar chairs the House Select Committee on the Chinese Communist Party, a congressional committee focused on U.S.-China issues.
Moolenaar said Nvidia’s resignation was unfortunate but that American companies should not give Chinese firms access to their most advanced chips. He called on Nvidia to appoint leadership that made national security its top priority and urged Congress to pass bipartisan export-control legislation in the year-end defense bill.
Palihapitiya read the statement as an indication of the terms lawmakers might demand. If tracking or shutdown systems were expanded, he asked, which institution would hold the keys: the NSA, CIA, Commerce Department, Bureau of Industry and Security, Treasury, or a new congressional body? The discussion named those possibilities without identifying one as the settled plan.
Sacks placed the current argument within the export-control framework he described. He said the Biden administration began restricting advanced semiconductors in 2022, barring leading-edge chips while allowing less advanced products such as the H20 to be sold in unlimited quantities without licenses. The Trump administration retained the distinction, he said, but moved lagging-chip sales to limited quantities and a licensing basis.
He objected to portraying support for sales of lower-performance chips as softness toward China. The original policy rationale, as he described it, was that sales could take market share from Huawei and direct revenue to U.S. companies, while limiting the scale-up of a Chinese competitor. Sacks said that if Congress wanted to prohibit all sales, he would accept the policy, but argued that the more nuanced arrangement had become politically difficult to defend.
There was a further complication in the Chinese government’s own policy. News headlines shown during the discussion reported that Beijing urged firms to shun Nvidia’s H20 chips, that Nvidia H200 chips were stuck in Hong Kong amid Chinese limits on customs clearance, and that China had blocked Nvidia AI chips in pursuit of semiconductor self-reliance. Sacks said China had both restricted H20 purchases and prevented H200 shipments from entering the country. He argued that the Chinese government wanted to promote Huawei, even as Chinese AI developers and companies wanted access to Nvidia hardware.
Friedberg agreed that those positions could coexist: companies building AI models covet the latest chips, while the state wants domestic chip champions. Sacks said Beijing was willing to accept short-term costs to force Chinese companies and developers toward local suppliers. He pointed to reporting that DeepSeek’s latest model was trained exclusively on Huawei chips as an example of that push.
That distinction complicates the claim that export controls necessarily deny China something its government is trying to obtain. Sacks argued that China’s leadership wants Nvidia chips kept out for a different reason from Washington’s China hawks: Beijing wants Huawei to scale and compete globally. Calacanis asked whether Jensen might have known chips were being diverted through Megaspeed or other intermediaries. He speculated that a technology leader who believed AI should benefit people globally might rationalize sales that complied with formal rules even if he suspected diversion. Friedberg questioned why Jensen would risk criminal consequences for additional sales. Sacks called the suggestion speculative and reiterated that the facts about Megaspeed and any knowledge by Nvidia or Jensen still required investigation.
Anthropic’s IPO puts its growth case against Nvidia’s infrastructure risk
Anthropic’s proposed IPO brought the market discussion back to the dependence of AI companies on infrastructure, capital and investor confidence. Calacanis described an offering of 825 million shares at $70 to $78 each, implying a valuation of roughly $1.4 trillion—below earlier reports of $2 trillion or $3 trillion. He said the financing would total about $90 billion, including $64 billion in share sales and $26 billion in a private placement. Seven founders planned to sell about $250 million each while retaining stakes he estimated at roughly $18 billion apiece. They had pledged to donate 80% of their holdings to charity, Calacanis said, though he did not consider the pledge legally binding.
He cited an $81 billion revenue run rate at the end of October and third-quarter revenue of $17 billion, compared with $10 billion for OpenAI. An AlphaSense slide shown during the discussion presented valuation estimates alongside projected revenue and spending commitments:
| Measure | Base case | Bull case or total |
|---|---|---|
| IPO valuation range | $1.26T–$1.41T | — |
| Expected 2028 revenue | $81B | $250B |
| Valuation multiple at $1.41T | 16–17× revenue | 5.6× revenue |
| Financing liquidity | $90.8B | — |
| Aggregate commitments, 2025–2028 | — | $900.9B |
The figures in the slide were presented as estimates and commitments, not as realized revenue or spending. Calacanis also cited a bull-case valuation of $4.2 trillion based on expected 2028 revenue of $281 billion, and said the target IPO valuation represented a 46% premium to Anthropic’s last private round.
Palihapitiya thought a large cash reserve would help Anthropic withstand economic uncertainty, but argued that much of the company’s valuation depended on conditions outside its control. He estimated that only 20% of Anthropic’s value came from Anthropic itself, with the rest depending on the broad economy, AI and Nvidia. If the market saw more risk in the Nvidia investigation or infrastructure investment, he said, investors could become more cautious about new offerings. He said the IPO was already six times oversubscribed, but thought its final price would depend heavily on what emerged before November 20.
Friedberg said he had not studied the valuation and framed his view as speculation based on what he had heard from people who attended management discussions. He said some investors believed Anthropic’s models were accelerating while compute cost per unit of intelligence was declining. Combined with investments across the infrastructure stack, including chips, that could support a winner-take-all outcome, he said. If investors believed that possibility had a meaningful chance of being true, he expected heavy demand, though he offered no formal valuation analysis.
Calacanis’s bullish case focused on Anthropic’s expanding product bundle. He cited Claude Meetings, Whiteboards, Sheets and Data, along with legal and personal-finance products and earlier work in coding, collaboration and design. In his view, a subscription that adds more business functions could challenge Microsoft and specialist SaaS companies, while reducing the friction of moving data between separate products.
Sacks saw the same growth ambitions as evidence of concentration. He said Anthropic was describing a winner-take-all market and presenting recursive self-improvement as a business advantage. For people worried about rapid AI development, he argued, that should be more concerning than Jensen’s support for open-source AI, which he said remained behind the closed-model frontier. Sacks called Anthropic a strong company and said he had invested in it; his criticism was that groups identifying with AI safety appeared to support a company pushing the frontier quickly while celebrating the departure of a founder associated with broader access.
That criticism rested on Sacks’s interpretation of the safety groups’ motives. He argued that if their priority were limiting rapid capability gains, they should be more concerned about Anthropic’s claims about recursive self-improvement. He suggested that some advocates instead wanted government control over chips and models. Palihapitiya added that Congress seemed more interested in pursuing other companies than Anthropic. The panel did not explain why lawmakers had taken that approach.
Dario Amodei’s prediction that cancer, Alzheimer’s, heart disease and mental illness could become “relics of the past” in less than a decade sharpened the difference between confidence and caution. Friedberg said AI was already changing molecular discovery and in-silico testing, and that biology breakthroughs using these tools were happening now. The speed of future progress remained uncertain, he said, but the work was not speculative or a decade away. He also said his own biology work used Anthropic for demanding tasks and that he considered its models the best for that work.
Calacanis called Amodei’s statement potentially reckless, while saying he believed Amodei meant it. Palihapitiya instead predicted a recession by 2028, underscoring how exposed the AI investment case may be to wider economic conditions.