The $31 Trillion AI Buildout Depends on Power, Politics and Public Consent
PwC’s Dallas Dolen argues that global AI infrastructure investment could reach $31 trillion through 2050 because demand for compute is likely to outpace efficiency gains. He says the forecast depends not only on data centers and chips but on new power supply, financing and government approvals—and on whether companies can win community support for projects that raise questions about local costs and resources. Dolen expects political and economic disruptions to shift the timing of construction more than erase the underlying demand.
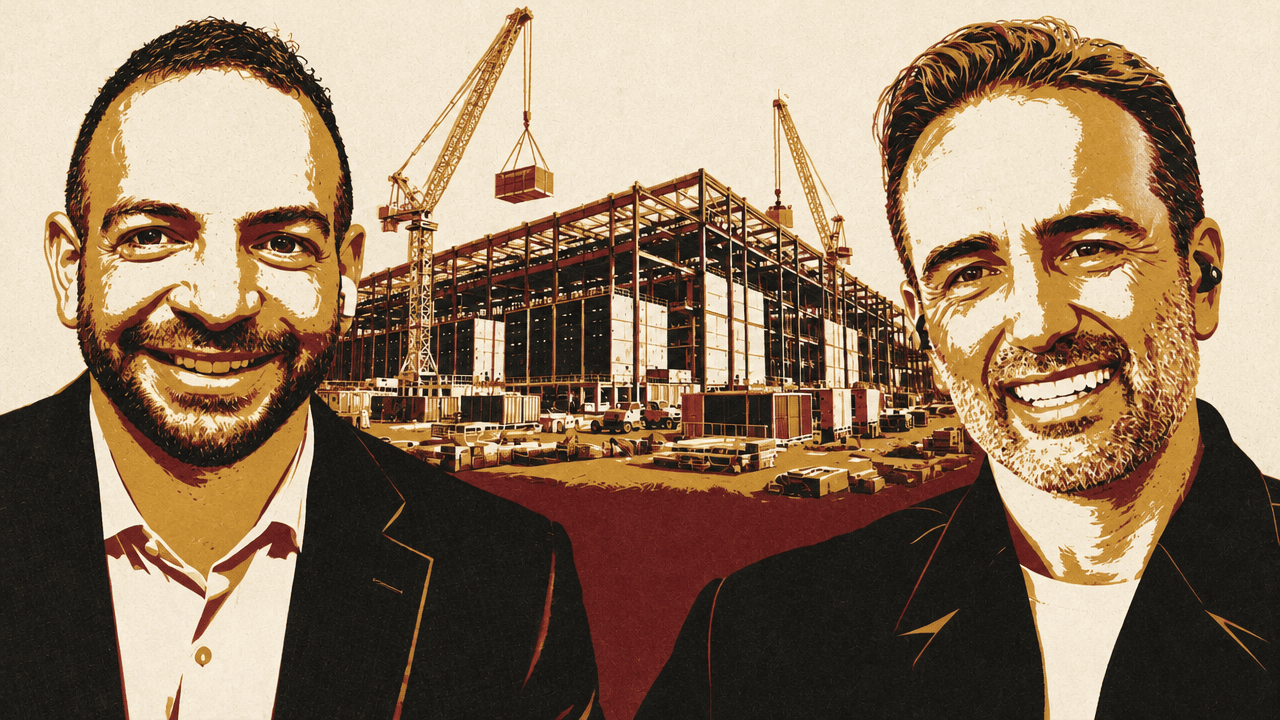
Demand may outrun efficiency, but demand alone cannot build the forecast
PwC projects about $31 trillion in global AI-infrastructure investment through 2050, with data-center spending reaching $1.8 trillion a year by then. Dallas Dolen says the total could be higher—perhaps $50 trillion, depending on how events unfold—because demand will come from more than the companies building the most prominent models.
For Dolen, the relevant measure is not just how much compute a particular model needs. It is how much data moves through AI systems, how many prompts people send, and how much activity involves cached information rather than new prompts. Frontier-model firms are one set of users; open models, enterprises and consumers are others. The infrastructure required to serve them—data centers, chips, memory and power—is part of the calculation.
That framing is central to Dolen’s answer to the efficiency objection. Kantrowitz asks whether models might become efficient enough to need less compute for the same output. Dolen points instead to the current imbalance: demand for compute already outstrips supply.
Demand for compute is vastly outstripping the supply for it. Just full stop.
Dolen says the shortage can be measured in computing capacity, access to tokens or energy. Looking four or five years ahead, he sees insufficient supply across all three. He points to throttling by some model companies and to services that can feel slower as usage rises. The growth is not confined to the largest firms, either: he cites increasing use of open models and broader adoption across consumers and enterprises. For infrastructure builders, he says, the identity of the eventual customer matters less than the expectation that overall use will keep expanding.
Dolen’s argument is that rising total use could outweigh efficiency gains. That is a distinction about the possible effect of efficiency, rather than a claim that efficiency does not matter: using fewer resources for an individual task would not necessarily mean lower total demand if the number of tasks keeps growing. He also points to markets where access and use have not yet spread as widely, including parts of Southeast Asia and Latin America, as potential sources of further demand.
The projection, however, depends on more than demand. Building enough infrastructure would require power, chips, memory and transformers, as well as approvals for the facilities that supply electricity. It would also require communities and governments to accept projects whose costs and benefits may be contested.
Power deals may help unlock supply; they do not settle who bears the costs
Power is both a physical constraint and a political question: who pays for new supply, who benefits, and what happens to local prices and resources. Dolen says the growing need for electricity could prompt companies, utilities and governments to coordinate on new capacity. A company that needs power can become a buyer working with providers and public authorities, rather than leaving the problem entirely to taxpayers and municipalities.
He cites Google in the Southwest, Microsoft in New York and xAI in the Midwest as examples of deals involving power alongside data-center or manufacturing projects. In his view, these arrangements could encourage companies and governments to plan together. He connects that possibility to supply problems and what he describes as a lack of reinvestment in infrastructure in some places. But collaboration is a possible route to addressing the power constraint, not a guarantee that a project’s costs or effects will be acceptable to nearby residents.
Dolen expects the $31 trillion forecast to face political as well as economic disruption. Elections could alter the outlook, with state-level decisions particularly consequential for projects involving data centers and power. He notes that fights over development often happen at the state level, even as federal elections attract more attention. He also says some current builds include local power-supply requirements, and suggests that arrangements responsive to community concerns could make development easier to support.
The United States leads in compute, while other regions compete for construction
Kantrowitz introduces 48% as the report’s projected US share of future data-center construction, a smaller share than the scale of the forecast might suggest. Dolen distinguishes the country’s current lead in actual compute from its ability to build quickly. The United States has significantly more compute than most other parts of the world, he says, but that does not mean every future facility will be built there.
Other governments are looking to attract investment. Dolen recounts conversations with people in Southeast Asia who want more data centers and related construction, including chip and memory production. He sees the region as a particularly strong example of governments seeking to draw investment, and names the Philippines and Vietnam among places where he expects more activity. He also sees potential in the United Arab Emirates, while cautioning that conflict and uncertainty make Middle Eastern projects difficult to assess in the near term.
The case for expanding across regions is tied both to population and to uneven access. Dolen points to Southeast Asia, Europe and Latin America as markets where use could grow as access spreads. His broader premise is that billions of people may eventually want to use the technology, and serving them requires more than models: it requires the data centers, chips, memory and power that carry the traffic.
Kantrowitz and Dolen each describe using translation tools to hold conversations across language barriers. Kantrowitz used ChatGPT Voice during a three-hour taxi ride in Indonesia; Dolen describes using WeChat and an AirPod to translate a three-hour conversation in Beijing. The examples make the prospect of broader consumer use tangible: if such tools bring more people into regular use, they add to the global demand Dolen expects. Dolen says his experience showed him how technology can help people connect across language barriers.
International competition may put pressure on the pace of development, but construction still depends on practical inputs and local decisions. Dolen names chips, memory and transformers as constraints, along with the approvals required to build power facilities. A country’s willingness to attract foreign investment cannot by itself make those inputs available or secure permission for a project.
Dolen expects the total to hold, but politics and borrowing costs could move the timeline
Asked whether the projected investment will actually be built, Dolen says he is “largely a buyer” of the $31 trillion figure. He expects disruptions that could shift timing and the mix of investors without necessarily changing the total, unless the economy suffers a major displacement.
His two main concerns are politics and macroeconomics. Elections could change the conditions for development, and state-level decisions may matter more directly than federal action for many projects. On the economic side, higher interest rates could make debt financing more expensive. Because infrastructure development relies heavily on debt, Dolen says, the result could be slower projects, a different mix of investment or different sources of capital.
He remains optimistic that investors will see the long-term growth potential and that capital will be available, but his confidence is conditional. A substantial downturn could change the picture; so could borrowing costs that make projects harder to finance. In that sense, the forecast is not a claim that every announced build will proceed on schedule. It is Dolen’s expectation that disruptions are more likely to move the timetable than erase the underlying demand.
Community consent is a constraint the industry has not explained well
Dolen says data centers can become politically divisive when concerns about water, power, land and government incentives are easy to connect to everyday costs. Residents may ask whether a facility will raise their power bills or draw on water they need, and why public money should support a project when schools, libraries and roads also need funding. Political actors, he argues, can use a divisive issue to raise money or win votes.
He says infrastructure owners and technology companies have largely failed to organize around a shared, truthful explanation of what a data center means for a county or state. In Dolen’s account, opponents can make a concise case for stopping a facility, while companies often explain the need to build in terms of serving customers or supporting their own businesses—reasons he thinks may not persuade residents.
Dolen points to Meta’s localized work with CBRE as an example of a more community-focused effort, but says it has not been widely scaled. Companies could show accurate information about resource use, explain local agreements and make a case about economic effects. He recalls a Georgia Tech study that, as he remembers it, found higher employment, wages and household income in counties after data centers were built. This is Dolen’s recollection of a study, which he presents as a potential talking point—not as a substitute for explaining the effects of a particular project.
Kantrowitz asks whether prominent executives such as Jensen Huang should speak directly to communities. Dolen does not insist that the industry appoint one leader, but thinks it would be useful to have a credible voice able to explain why the buildout matters and what local communities can expect. Whoever takes on that role, he says, would face criticism. The companies would still need information and a case they could defend.
For Dolen, the public argument has two connected parts: explaining why infrastructure should not harm communities, and showing people how AI can help them. Consumer-facing applications may make the technology’s benefits more concrete, but they cannot replace a direct account of local resource use and costs.
Current models may be useful enough; organizations still have to put them to work
The infrastructure case also depends on what people and organizations do with AI. Kantrowitz asks what would happen if progress stopped at today’s level. Dolen’s answer is that current models are already useful, and that weak returns in many organizations reflect a failure to apply them well more than a lack of capability.
Dolen cites reports in which AI use is widespread across enterprises but only a small share report benefits: roughly 7–8% in one account, with other reports putting the figure around 12%. He does not treat those numbers as evidence that the tools are inadequate. He argues that organizations lack top-down direction about where and how to use them, across functions such as sales, marketing, product development, finance and back-office work.
Rapid releases may contribute to hesitation. A company that adopts one model may worry that a better one will appear days later. Dolen calls this a form of fear of missing out, but says choosing a capable tool does not mean forfeiting the opportunity. The direction has to come from within teams, business units and schools, not only from a CEO.
A consumer example makes the potential less abstract. Dolen recounts his 15-year-old son texting shortly before an algebra test, worried that he would fail despite studying. Dolen suggested that, for the next test, they build a prompt together and use a model to create a customized study course. He says that kind of support could be valuable to a household and notes that many of the tools are currently available at little cost.
Kantrowitz suggests that a pause in model releases might give organizations time to settle on tools and make them profitable. Dolen agrees that builders want to sell newer models, but compares the cycle to buying better golf clubs: improved equipment may help, while improving one’s use of existing equipment can also make a difference. Not every user needs the newest tool.
The practical obstacle, in Dolen’s account, is not waiting for a model that can do more. It is deciding where current tools fit, giving teams direction and committing to ways of using them. He argues that organizations can begin that work with the models already available; continual releases do not have to become a reason to postpone adoption.