GPU Forward Curves Point to Rising H100 and B200 Prices
Carmen Li, CEO of Compute Exchange and Silicon Data, argues that buyers should procure GPU capacity through a neutral exchange rather than negotiate separately with hundreds of providers. Drawing on her experience as an energy-options market maker, she says an exchange can verify buyers and sellers, compare offers and support reserved and forward contracts without owning the GPUs it trades. Li also points to Silicon Data’s forward curves, which she says indicate that the market expects H100 and B200 prices to rise.
Compute procurement needs a neutral market, not another sales channel
Carmen Li argues that the growth of GPU providers has widened buyers’ choices while making procurement harder to coordinate. She says there are more than 300 new private cloud providers globally, alongside hyperscalers, token factories and API routers. A buyer can contact providers one by one, but that makes it harder to compare offers and establish whether promised resources will be delivered.
Li’s analogy is the stock market. Buyers can call brokers or banks, she says, but an exchange makes it easier to find counterparties, execute a transaction and settle it. The exchange does not guarantee the best price simply by existing; its value is that it makes liquidity and transactions more accessible. Compute Exchange applies that model to reserved GPU capacity, forward contracts and token packages.
The company says it has more than 100 verified providers and over 80,000 GPUs in supply, across the US, Europe and Asia-Pacific, excluding China. It aims to return quotes within 24 hours. Li describes its role as a neutral intermediary that verifies supply and demand, routes requests to suitable providers and presents offers.
Neutrality, in her account, depends on not owning GPUs. If Compute Exchange operated compute itself, it could have an incentive to favor its own capacity, select clients or retain customer relationships. Instead, Li says, it handles transactions individually and connects buyers and providers without owning the underlying resources.
Verification is central to that role. For existing reserved capacity, the company says it checks GPU identifiers, inventory and performance, using tools including NVIDIA DGX, InferenceX and MLPerf. For future capacity, it reviews documents such as purchase orders as part of its due diligence. It also checks buyers through know-your-business and know-your-customer processes, giving providers a basis for assessing whether a customer can pay at the agreed rate.
Li connects this model to her earlier work as an energy-options market maker at DRW Trading. She distinguishes between contracts designed for financial hedging and those intended for physical procurement: in her comparison, Brent is useful for hedging price exposure, while physically delivered WTI serves buyers seeking the commodity itself. Compute Exchange, she says, is building toward the physical-procurement side of that market. The forward contracts it facilitates are a precursor to physically delivered futures.
Reserved, forward and secondary markets serve different needs
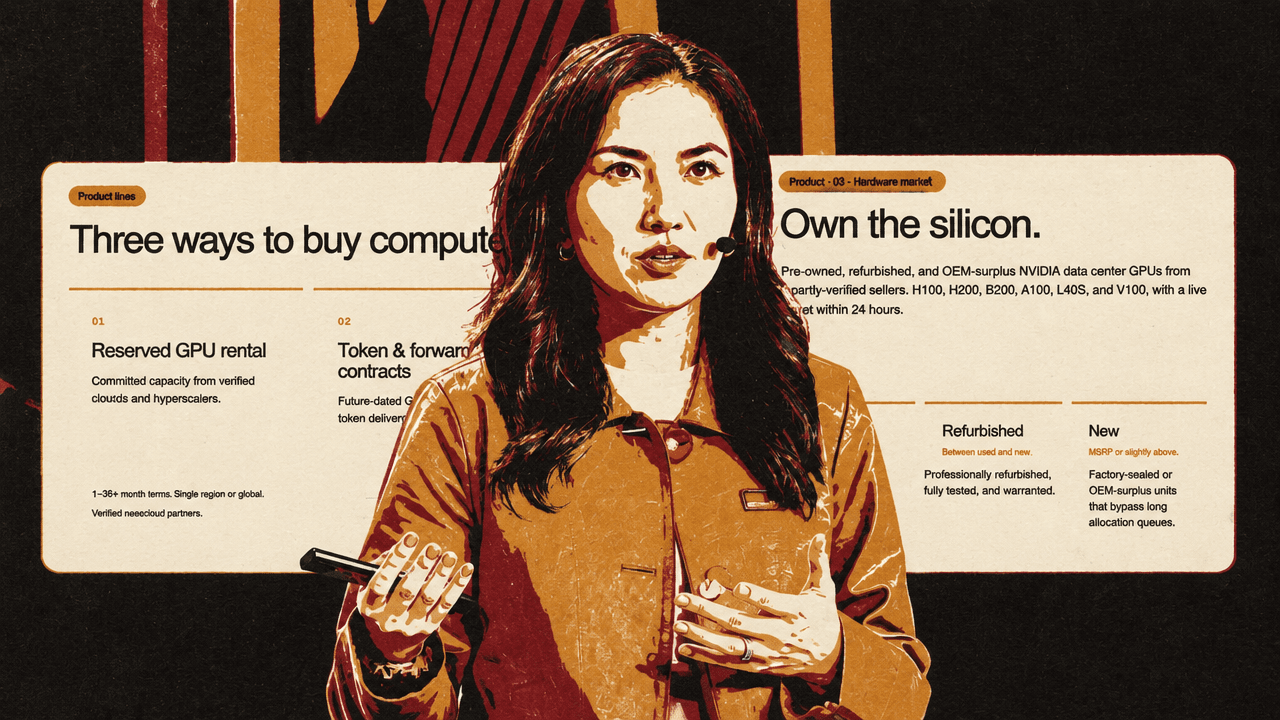
Compute Exchange organizes its offering into three markets: reserved GPU rental, GPU and token forward contracts, and an open hardware market.
Reserved contracts let a buyer commit to capacity for a defined term. Li says the minimum is one node for one month; longer contracts can extend to three, four or five years, depending on availability and provider terms. The company does not offer on-demand compute. Buyers can state preferences and compare providers through a normalized quote. Li also says the platform offers a way to sell capacity back to Compute Exchange if a buyer has overcommitted on quantity or duration.
Forward GPU contracts address a different problem: a buyer needs capacity at a future date, but it is not available now. Buyers can post bids for future capacity, while providers can offer capacity they expect to have. Compute Exchange matches counterparties, with terms negotiated bilaterally.
Token forwards extend the idea from hardware to inference. Li describes these as a dedicated deployment: a customer reserves a GPU cluster and receives a dedicated token deployment on top of it. The customer can fix a model, service levels and quantization precision for a period, rather than relying on potentially volatile on-demand token API pricing. The company’s presentation frames this as a way to set the cost per million tokens before launch.
The secondary hardware market grew from requests to sell large amounts of used equipment. Li recalls being asked whether Compute Exchange could take 20,000 H100s sitting in a data center. That led the company to establish a marketplace for secondary server sales, which she says has been active for about a year. It covers used and refurbished hardware, as well as new or OEM-surplus units, across models including H100, H200, B200, A100, L40S and V100. Li also mentions AMD GPUs and consumer 4090s.
Prices in this market do not always follow a simple discount-to-new pattern. Li says B200s have sometimes traded above MSRP, comparing the situation to secondary cars selling above new-car prices during COVID. The company’s product materials distinguish used equipment, sold as-is with condition documented, from refurbished equipment that has been inspected and tested, and new or surplus units that may bypass long allocation queues.
A quote process routes requirements to providers and compares their offers
A buyer can browse listed compute pools or submit a request for quote if available listings do not fit. The request form collects the GPU vendor and model, deployment type, cluster architecture and GPU count, along with preferences such as interconnect, CPU platform, storage, software stack, region and use case. Li says the platform sees “over a billion” RFQ’d each month, but does not specify what the figure measures. She describes requests ranging from a single node to 20,000 nodes.
Compute Exchange tracks providers’ current and anticipated inventory, then routes a request to providers it believes can meet the requirement. For example, Li describes a buyer seeking 300 B200 GPUs in US East starting January 1: the team might identify three potential providers and send the request to them. The buyer receives their offers through the platform, with pricing, specifications and service-level agreements compared against the same requirement. For existing servers, the company says it benchmarks the equipment.
Price is not the only criterion, Li says. The platform brings the terms together so buyers can compare offers, then introduces the buyer and provider rather than holding the relationship. “We never hold relationships,” she says. The platform also keeps negotiations in its messaging system while the parties work through unclear terms or practices.
Compute Exchange scores buyers and individual requests, Li says, to determine what reaches providers and how quickly. The company’s displayed verification process covers provider corporate registration, beneficial ownership, operational track record and signed partner agreements. Its systems track requests through routing, quote review and deal status, while provider inventory can arrive through channels including Slack and email.
Li reads the forward curves as a signal of higher future prices
Li also runs Silicon Data, which she describes as a data provider for compute markets. She says its indices will be used by CME to settle futures, with H100 neocloud on-demand rates and B200 prices expected to begin trading in a few weeks. At the event, she used Silicon Data’s term-implied forward curves to show how the pricing of reserved GPU capacity had changed.
These curves are calculated from reserve-contract term structures; Li emphasizes that they are not observed futures prices because futures are not yet trading. The horizontal axis shows contract duration and the vertical axis shows price per GPU per hour. In her description of the H100 chart, last year’s curve sloped downward: longer commitments came with lower hourly prices. Starting early this year, she says, the curve shifted upward and became contango. Li interprets that change as meaning longer contracts were no longer discounted enough, in her view because market participants assumed prices would rise.
She says the curve continued shifting upward and then flattened, narrowing the price difference across contract lengths. Her reading of the implied forward rates is that market consensus points to higher prices over the next 36 months. She cautions that “market consensus doesn't mean it's right.” This is an inference from the term structure, not a forecast guaranteed by future trading.
For B200, Li says the curve was in contango last year, then shifted upward across every term and flattened. She interprets the implied forward rates as pointing toward higher prices as well. The charts therefore show changes in the prices attached to different reservation lengths; Li’s explanation is that the market is pricing in rising costs.
The term structure matters, she argues, for operators whose financing obligations outlast their customer contracts. A company might have servers financed for five or six years but reserved contracts covering only the first three, leaving exposure in years four through six. Li says swaps or block trades can help address that risk. Even an operator with three years of reservations faces the possibility that a reservation counterparty defaults. She says Silicon Data has seen block trading around the indices, including trades structured at floating rates.
Silicon Data’s residual-value estimates sit above the displayed depreciation benchmark
Silicon Data also estimates residual values for GPU servers. Li describes the method as a forward-looking discounted-cash-flow calculation: projected cash flows from a lease are discounted to estimate an asset’s current value. The estimate depends on assumptions including utilization and costs, which she says the company makes transparent. Silicon Data calculates normalized values across A100, H100 and B200 servers, then compares them with an accelerated-depreciation benchmark.
A chart attributed to Silicon Data and Cloud API/Reseller Availability displayed Silicon Data’s modelled residual-value estimates alongside the benchmark. It showed 58% for A100, 103% for H100 and 115% for B200, compared with 25% at year two for the accelerated-depreciation schedule.
Li says A100 values are declining but remain above the chart’s depreciation curve. She describes H100 prices as having risen and says B200 GPUs have traded above MSRP. Those statements about trading prices are distinct from the chart’s modelled residual values.
Li says Silicon Data’s estimates are used by some banks appraising GPU servers on their balance sheets. She also says NVIDIA cited Silicon Data in its September Investor Day deck, describing it as the only data provider cited there.