Live Commerce Could Exceed 30% of E-Commerce Within a Decade
Whatnot founder Grant LaFontaine argues that live commerce will become a major share of e-commerce because it gives small sellers a way to demonstrate products, build audiences and operate beyond the constraints of a physical shop. He says Whatnot’s growth—from a Funko-focused marketplace to a platform whose sellers span categories from collectibles to seafood—came from starting in a narrow community, generating demand before recruiting supply, and treating live selling as a primary business rather than an add-on channel.
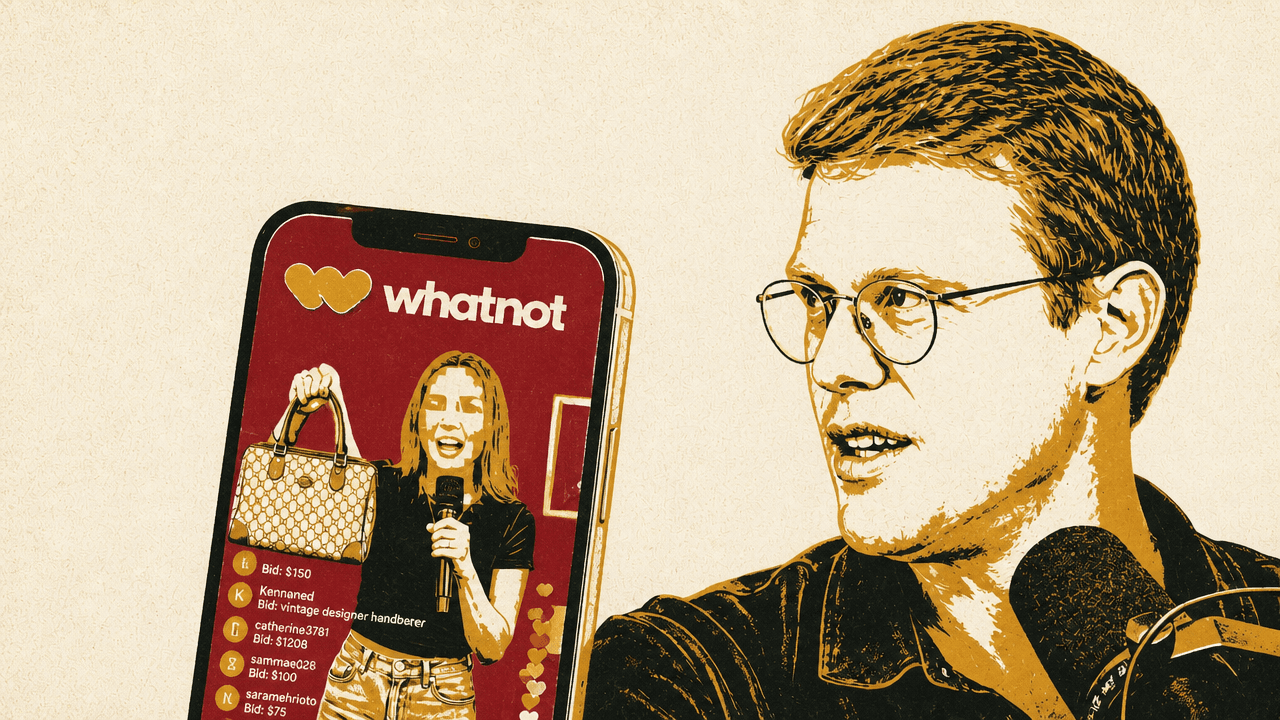
The bet was not on Funko Pops; it was on a different way to shop
Grant LaFontaine does not describe Whatnot as a collectibles company that happened to get large. The company began with Funkos, Pokémon cards, and other nostalgia-driven goods, but its underlying thesis was that shopping could be more social, more entertaining, and more useful for sellers than a conventional listing marketplace.
That thesis now encompasses a far wider set of goods. The app presents live streams in which sellers run auctions, flash sales, giveaways, and chats around categories including sports, fashion, collectibles, food, and specialty products. During the discussion, Shaan Puri bought a half-dozen Maryland blue crabs from a live seller for $34.
The on-screen seller profile for iLoveCrabs, identified as Harbour House Crabs, listed a 4.9 rating across 643 reviews, an average shipping time of under a day, 3,300 items sold, and 13,500 followers. Puri’s rough calculation was that the seller had made more than $100,000 selling crabs online. The profile described the business as delivering fresh Maryland crabs and seafood for more than 25 years; its live-auction cards advertised flash sales, giveaways, and live shows.
For LaFontaine, the oddity of the inventory is evidence of the format’s range, not a distraction from it. Seafood is his favorite category on the app; he said he had recently hosted a full crab boil sourced through Whatnot. In the model he describes, live selling lets buyers see where a product comes from and encounter the person selling it more directly than through a conventional listing or supermarket shelf.
LaFontaine forecasts that live commerce will become more than 30% of e-commerce over the coming decade, up from what he characterized as a single-digit percentage today. He estimated that the three largest live-shopping players across the United States and Europe currently account for roughly $30 billion in sales. His comparison point is China, where he said live commerce represents about 40% of e-commerce.
That forecast rests on the seller model LaFontaine sees emerging. A small merchant can reach buyers beyond the radius of a physical store, demonstrate products in real time, build repeat viewership, and make a stream into a primary business rather than another passive sales channel. During COVID, LaFontaine said, some comic-shop owners joined Whatnot after foot traffic stopped and discovered their sales on Whatnot could exceed those of their former brick-and-mortar shops. He said the business continued to perform strongly after that period, which he took as evidence that the product’s value was not solely pandemic-driven.
The upper end of that seller economy is already substantial, by his account. Whatnot’s largest sellers do well over nine figures in sales, and there are multiple such sellers. One of the largest operations he described began with three or four people, built almost entirely on Whatnot, and expanded to roughly 150 to 200 employees. The sellers are not necessarily established retailers that decided to add a streaming channel; some began as small operators who moved early and built organizations around live selling.
LaFontaine expects live commerce to produce its own supporting industries if the market develops as he forecasts. He identified wholesale supply for sellers who need inventory at scale, as well as multi-channel networks that help merchants operate and grow live-shopping businesses. If US live-commerce sales reach the several-hundred-billion-dollar range he imagines, he argued, many large seller businesses would emerge.
A marketplace begins by becoming its own seller
The conventional difficulty in a marketplace is that sellers need buyers and buyers need supply. Whatnot’s early solution was not to solve both sides at once. It became the seller.
Grant LaFontaine and his co-founder Logan were initially building what LaFontaine calls a “better full-service Craigslist”: a marketplace for used goods that would improve the customer experience through services such as delivery. The idea collapsed quickly under basic unit economics. LaFontaine called delivery operators at furniture and other companies to understand their costs, then concluded that the cost of moving low-value used goods left no workable margin.
The team was tiny—LaFontaine, Logan, an engineer, and a part-time designer—and the company changed direction while its core marketplace infrastructure was still being built. The early engineer was based in Brazil and was paid relatively cheaply in cash plus equity; the designer was given equity for branding and design work. LaFontaine had roughly $100,000 to $200,000 available personally, excluding his retirement account, and funded the company “check by check” before raising money.
The search for a new market led back to eBay. LaFontaine had sold Pokémon cards online as a child, and he and Logan saw a broader resurgence in collectibles. They used an eBay-category data tool, which LaFontaine recalled as Terapeak, to chart sales over time. Every collectibles category they examined was growing sharply. Funko Pops, at the time, were selling in greater volume on eBay than comic books; Funko and Pokémon became the first categories Whatnot considered.
The choice was not based only on aggregate demand. LaFontaine and Logan visited Los Angeles comic shops and found them packed with collectors and Funko inventory. They believed that a product experience largely unchanged for two decades could be rebuilt around discovery and community: people finding items, talking to others with the same interests, and shopping in a more social environment.
An archived March 2020 Whatnot interface shown on screen made that early positioning explicit: “Buy & Sell Authentic Collectibles,” with fandoms including Disney, Marvel, Rick & Morty, Sports, Star Wars, and Walking Dead. The interface also highlighted Pokémon cards. A second on-screen capture described Whatnot as the “Largest Catalog of Authenticated Funkos, FiGPiNs and more,” emphasizing professional authentication, low fees, and seller protection.
Their early marketplace did not actually hold all the items it displayed. Whatnot positioned itself as the seller and offered authentication as an additional service. It built a catalog that could not simply be stocked in advance—LaFontaine said there were on the order of 100,000 Funko products—and then sourced an item after a buyer ordered it.
That required more than posting a photo and hoping supply could be found. Whatnot scraped sites carrying Funkos, built a pricing algorithm, tracked the liquidity of each item, and imposed a liquidity floor. A product with only one sale in 90 days could not be reliably sourced. The company instead used recent sales and the rate at which an item traded to set a price at which it could secure the product, authenticate it, and resell it. A team in Brazil helped locate inventory from roughly a hundred online stores.
The system was imperfect. In the first month, Whatnot made about 30 sales, and LaFontaine said buyers found errors in its algorithm that let them buy expensive collectibles far too cheaply—for example, a $500 Funko for $150. But operating as the initial seller gave Whatnot a way to create a buyer experience before it could credibly recruit independent sellers.
| Period | Whatnot milestone | Sales or scale disclosed |
|---|---|---|
| December 2019 | App launches; the first two weeks generate one sale each | About 30 sales in the first month |
| March 2020 | Four months into the company and recently out of YC | $20,000–$25,000 in total transaction volume |
| July 2020 | First live-auction product launches | Growth begins to inflect |
| Year-end 2020 | First year after launch closes | $2.3M in total sales; roughly 17–18 employees |
| Year-end 2021 | Live format and category expansion compound | $163M in total sales; roughly 100 employees |
| Following year | Marketplace continues expanding | $1B in total sales |
The first independent sellers were not invited until roughly the end of February 2020, once there was enough buyer demand. Even then, Whatnot tried to ensure that sellers saw activity. It gave them access to its existing audience and cross-listed inventory to other marketplaces through Whatnot’s own account. The aim was not a refined retention model. LaFontaine said the data was too sparse for that. The practical objective was simply to get sellers enough sales that they would stay.
Early growth came from tactics incumbents could not justify
Sam Parr framed Whatnot’s early playbook as the kind of “gritty internet entrepreneurship” founders may be reluctant to describe once a company is large. LaFontaine did describe it: influencer outreach, giveaways designed to be shared repeatedly, and a willingness to start with mechanisms that did not look polished.
The buyer-acquisition strategy had two principal elements. First, Whatnot partnered with Funko influencers on YouTube. In December, before the product had much credibility, Grant LaFontaine said he called every Funko influencer he could find. Most did not trust the unknown company. One connection from his prior work provided an initial foothold.
Second, Whatnot created a viral giveaway system around “grails” and “chases”—rare, desirable items within collector categories. Each week it gave away a $500 or $1,000 Funko. Participants could gain entries by sharing a referral link or code on platforms such as Twitter and Instagram; a new user joining through that link generated another ticket. The mechanic encouraged collectors to share repeatedly, and LaFontaine said it helped Whatnot take over Funko subreddits and Facebook groups because it was giving away the items those communities most wanted.
The first giveaway was a failure. A $500 item attracted 104 total entries, perhaps 30 or 40 accounts, and generated no purchases. Because the company had little money and LaFontaine was personally financing it, the loss felt consequential. But he did not treat the first result as conclusive. The accounts acquired in the first raffle could receive notifications about the next one. If participation rose from roughly 100 entries to 300, the company could see the beginnings of a compounding referral loop.
The second giveaway was closer to 250 entries, by LaFontaine’s recollection. That was enough to suggest a direction. In his telling, the judgment required in a startup is partly about distinguishing a genuinely failed idea from a mechanism that has not yet had enough opportunity to compound.
If you try and copy the obvious pathways, you're basically going to get stonewalled because you don't have the resources.
That is why Whatnot spent virtually nothing on paid advertising in its early days, LaFontaine said. The company spends heavily on paid ads now, but it could not have made them work when it lacked capital, a mature product, and marketplace liquidity. The early task was to find advantages larger companies would not or could not exploit.
The founders were thinking in those terms even before they had settled on collectibles. On a holiday trip to Tokyo, frustrated with their jobs and interested in building again, they bought roughly 50 domains for possible marketplace ideas. One plan was to use SEO-oriented domains such as one targeting used Pelotons. Their initial “full-service Craigslist” concept was poor, LaFontaine said, but the instinct to seek unconventional routes to demand was present from the start.
The company later found its decisive product shift through a similarly practical process. When Whatnot entered Y Combinator in early 2020, it was a Funko marketplace growing modestly. LaFontaine said investors broadly disliked the business when the company tried to raise money during COVID. But Y Combinator backed it, and then continued to support it when other prominent investors passed.
LaFontaine attributes some of that to execution. Before its YC interview, Whatnot built and launched its product in roughly a week so it could discuss a real operating service rather than a concept. Logan had led engineering at sizable resale marketplaces; LaFontaine had worked at Facebook and YouTube and had previously started a company that was acquired for talent. Those backgrounds did not make the Funko thesis self-evident, but they demonstrated an ability to build.
The live product, launched in July 2020, changed the trajectory. Total transaction volume rose from roughly $20,000 to $25,000 in March to roughly $250,000 to $300,000 in September. The marketplace was growing at more than 100% month over month, LaFontaine said. Whatnot ended 2020 at $2.3 million in total sales, then reached $163 million the following year and $1 billion the year after that.
Small markets are not a concession; they are how consumer companies get started
Grant LaFontaine’s objection to the “Funko Pop company” label is also an objection to a common investor instinct: that startups should begin by addressing a visibly enormous market.
When Whatnot first launched live auctions and was growing rapidly, investors worried that Funkos were too small a category. LaFontaine thinks that framing mistakes the sequence. Great consumer companies, he argued, almost always begin in a very narrow market because a four-person startup cannot create a substantially better experience for everyone at once. It must concentrate on a smaller group, make something markedly better for them, and use that position to expand.
Shaan Puri compared the pattern to PayPal’s early traction among eBay sellers, rather than the broad online-banking vision associated with X.com. LaFontaine accepted the general principle while allowing for exceptions: every consumer success case he knows followed the niche-first path.
He also pointed to eBay. The familiar PEZ-dispenser origin story may be a public-relations simplification, he said; his understanding is that the first item sold was a broken laser pointer to a broken-laser-pointer collector. Whether or not that account is the memorable one, the point for LaFontaine is that successful marketplaces can begin in seemingly trivial corners of commerce.
This is part of a broader skepticism toward founder mythology. Whatnot describes itself as user-driven rather than vision-driven—not because it rejects having a view of the future, but because customer response has priority over a founder’s initial idea. A company may need direction, he said, but an idea customers do not want is fatal regardless of how compelling the story around it sounds.
No matter how great your vision is, if customers do not want that, you're dead to rights.
LaFontaine sees business narratives as often serving a social function: they persuade people to follow a founder. The more important work lies underneath the story, in the specific mechanics of customer value, supply, product behavior, and execution. That is why a small category can be strategically valuable. It gives a team enough focus to understand those mechanics deeply before the company generalizes them.
Whatnot’s expansion depended on turning that focus into a repeatable category-launch process. LaFontaine said the first 30 hires were exceptionally strong and that the company learned how to introduce multiple categories quickly. As categories proliferated, buyers and sellers in each could cross-pollinate, allowing the marketplace’s discovery, seller tools, and audience to compound rather than be rebuilt from scratch.
The operating principle is to make every abstraction earn its place
At 1,400 employees, Grant LaFontaine says the company needs systems, process, and a CEO operating rhythm. There were periods when accountability was not high enough and growth or focus drifted, he said. Scaling required building a system for making decisions, maintaining direction, and executing quickly.
But he rejects the idea that a founder must become a conventional corporate executive. Whatnot made mistakes when it tried to become too corporate too quickly, hiring executives from prominent companies on the assumption that pedigree established competence. A person who ran a function at a famous company may indeed be capable, he said, but the useful question is whether that person can explain in detail what they did, how they did it, and why it worked.
LaFontaine’s preferred management method is to keep reducing problems to their simplest defensible form: What is happening? How do we know? What are the mechanics?
He illustrated the approach through marketplace discovery. Whatnot’s recommendation feed allocates attention across sellers, categories, and countries. As supply grows, the platform must balance competing needs: comic books, women’s fashion, fresh food, the UK, and more. A discovery team may conduct detailed analysis and A/B tests, but LaFontaine argues that a familiar experimental framework can be unreliable in a networked marketplace because it may not capture the full dynamics.
In the example he gave, changing a feed changes what buyers see; buyers then enter different streams; sellers respond differently; and both sides of an A/B test can be affected. In his view, the test may therefore fail to isolate the effect the team thinks it is measuring.
When a macro metric declined despite apparently favorable test results, LaFontaine pushed the team to examine individual sellers, changes in their impressions across categories and countries, and the distribution of winners and losers. The key insight, he said, was about elasticity: some sellers’ businesses contract more from losing impressions than other sellers’ businesses gain from improved engagement. A change that improves near-term buyer engagement in a test can, by his account, still damage the marketplace at a broader level.
The language can sound technical, but LaFontaine insists the core question is ordinary: when a platform sends a seller more or fewer viewers, how much does that seller’s business grow or shrink? A platform that directs traffic should know that.
If you start to use a bunch of fancy words, I'm going to make you explain it to me like I am in middle school.
His view is that technical vocabulary often conceals weak understanding. People in technology, especially highly credentialed people, may enjoy sounding sophisticated; leaders have to keep asking until the actual causal claim is plain enough to test. If it cannot be explained simply, he said, the person presenting it may not understand it either.
That posture can feel adversarial, and LaFontaine acknowledges that intensive challenge is unnatural. Whatnot tries to make the culture about reaching the right answer rather than protecting status. New executives are told their prior methods are not beyond challenge; at most, those methods are neutral until they can be examined in Whatnot’s specific context. Maintaining that culture becomes harder when hiring hundreds of people in a year, but he sees continuity in long-tenured teams as important: people learn that detailed questioning is not meant as personal attack.
The difficult part is preserving rigor without becoming destructive. LaFontaine says that, in the early Slack days, feedback could be blunt: bad work was called bad and asked to be fixed. At 1,400 people, a founder is no longer interacting only with close collaborators who understand that style. He has had to soften his delivery because telling someone “this sucks” may not bring out better work from them; it may simply make them shut down.
That lesson was shaped by his time at Facebook. LaFontaine described working on a heavily politicized project that involved senior executives who could not agree. After weeks of late nights trying to resolve it, he brought the work to a product review where the leader running the meeting began yelling at participants. The experience contributed to his decision to leave. In retrospect, LaFontaine said, he can identify the management failure: whatever the quality of the work, that handling would not make people want to do more great work.
He is not claiming to be endlessly patient. He says there are times he is less kind than he would like to be. But the governing standard is instrumental as much as moral: imagine being in the other person’s position and ask what would help them perform at their best. Being mean, nasty, or combative will almost never achieve that.
Speed is a discipline, not an identity
Grant LaFontaine’s operating instinct is an “immense bias to action.” When delivery economics disproved Whatnot’s first business model, the team did not wait for a complete replacement plan before continuing to build reusable marketplace components. They learned enough to abandon the premise, preserved what could still be used, and redirected the company.
That approach informs his bluntest maxim:
If you think you're moving fast, you're probably not.
His claim is that organizations which talk about moving fast are often already moving slowly. If a team has time to congratulate itself for speed, it can probably find more. The point is not motion for its own sake. It is a refusal to mistake a self-image of urgency for actual execution.
LaFontaine applies similar restraint to Whatnot’s scale. Puri opened by noting that Whatnot was valued at $20 billion, a figure he compared with the combined market capitalizations of several well-known public companies. LaFontaine called the valuation “absolutely nuts,” but says he tries not to focus on it. Fixating on the number risks making the work feel complete.
He does allow himself brief moments of reflection. The company has made it possible to care for his family, created work for 1,400 employees, and supported hundreds of thousands of businesses that he says are collectively generating billions of dollars in sales. But those facts also produce obligations: responsibility to employees, and to the investors from whom Whatnot has raised $1.5 billion.