Founders Win Through Different Play Styles, Not One Universal Archetype
Sam Parr and Shaan Puri argue that founders win in different ways, and that the “natural money-maker” is one distinct play style: someone who repeatedly spots and pursues returns across businesses, often with a cool eye for deals rather than a single career plan. Parr identifies three traits in that type—being unemotional about business, maximizing returns and tolerating complexity—while Puri says unfamiliar deals can look simple once the path through them is clear. They present other founder archetypes as exploratory labels, not a fixed ranking or taxonomy.
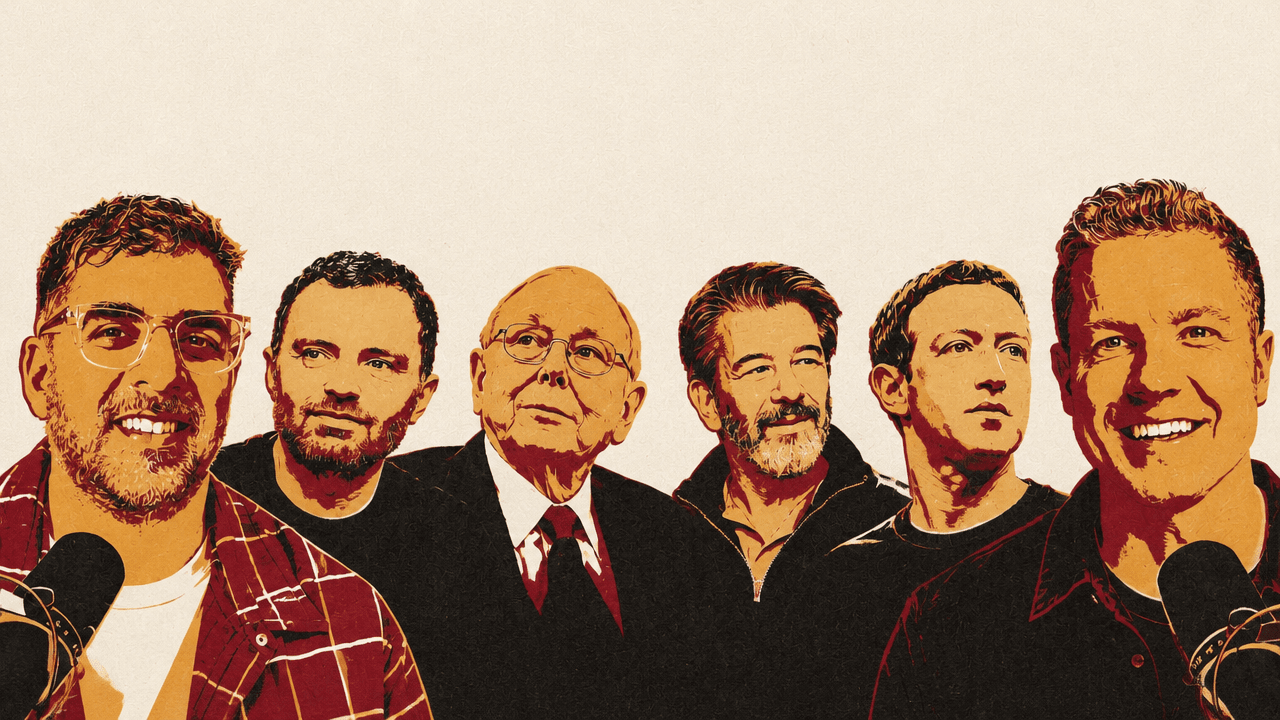
The natural money-maker wins across different games
Sam Parr uses “natural money-maker” for someone who repeatedly finds ways to make money across businesses and industries, often by brokering deals or inserting themselves into an opportunity rather than building in public. The distinction matters to him: a strong founder or CEO might have vision, recruit well, or understand a market. The natural money-maker has those abilities, too, but is unusually cold and logical about money.
Shaan Puri describes the pattern as a high hit rate. Many entrepreneurs fail several times before a success; natural money-makers, in Puri’s impression, seem to win, lose, then win repeatedly. They may not be the best manager, designer, or operator in any one setting. Their advantage is a kind of instinct: a “great nose” for where money is being made, where it is being wasted, and where a deal is hiding. Asked to explain how they saw an opportunity, they may offer less a detailed theory than a fast judgment.
Parr identifies three traits he has noticed in people he puts in this category: being unemotional about business, maximizing returns, and being comfortable with complexity.
The example Puri gives is Nick Kokonas, who studied philosophy in college, liked mathematics, and decided he wanted to become a trader. He received offers for banking jobs, but not the trading role he wanted. Trading, as Puri describes it, meant running a book of business and making high-stakes decisions quickly. Kokonas told him he could win or lose hundreds of thousands of dollars in a day.
Puri says Kokonas’s best year came from an arbitrage in the early days of exchange-traded funds: the price of an ETF could differ slightly from the real-time combined price of the stocks it represented. Kokonas saw that spread as an opening. To act on it, Puri says, he arranged a fiber connection between the New York and Chicago exchanges, where faster price information could matter against a system still relying on phone calls and paper slips. Puri says Kokonas’s company made $100 million in profit from one such arbitrage in its best year.
Kokonas then moved into restaurants, a field Puri describes as notoriously difficult to make money in. He partnered with chef Grant Achatz to build Alinea, publicly declaring the aim of creating America’s greatest restaurant—and framing the ambition so that a failure to award it three Michelin stars would reflect on the guide. Puri says Alinea was the first Michelin-star restaurant outside New York and, at its peak, brought in about $26 million a year with nearly 20% profit. He says the restaurant group made money during COVID by shifting to $35 takeaway dinners. After the interview, Kokonas was already talking to Puri about another deal: buying a million-dollar wine collection for $150,000.
For Parr, the point is not that Kokonas followed a single career plan. It is that he keeps finding deals. Parr describes a wealthy mutual friend who, while out with them, was looking into buying defaulted or soon-to-default credit-card debt, then paying a collection firm to pursue it for a projected return of roughly 14%. Parr wondered why someone already wealthy would bother with a relatively small opportunity. That question leads to the next trait.
They keep pursuing returns others would leave alone
Parr calls natural money-makers maximizers. They do not treat diminishing returns as a reason to stop: a small return is still a return if the effort and risk make sense to them. Where Parr might decide an extra investment is too much trouble, he says, these people keep looking. He compares the attitude with his own preference for index funds: even a small additional spread from direct indexing can seem like more trouble than it is worth to him. The natural money-maker, in his account, does not stop at “good enough” so readily.
He illustrates the appetite with a story about 19th-century railroad baron Jay Gould. As Parr recounts it, Gould was seriously ill with tuberculosis, his wife had died, and his family urged him not to take on another railroad deal. He initially said he would think about it. At a later family meal, he announced that he had decided to return to his “first love,” making money, and pursued the deal. Parr says Gould died about six months later. He offers the story as an extreme case of a drive that does not switch off: for the maximizer, “the perfect number is more.”
Puri sees something similar in Charlie Munger, whom he says continued to make investments late in life and made money in different ways, including through Berkshire Hathaway, real estate, a law practice, and newspapers. What connects these examples, in their account, is not one particular sector or technique. It is the repeated search for an opportunity—and a willingness to keep doing the work even when another person would think the existing returns are enough.
Parr links this maximizing tendency to being unemotional about business. He says natural money-makers can be anxious like anyone else; the difference is that they use their emotions to make money. He contrasts that with founders whose passion and emotion help them recruit and rally people. The natural money-maker, as he sees it, is more likely to look at the numbers and act without being held back by the discomfort of cutting something that seems wasteful.
Parr’s example is Carl Icahn, whom he describes as a 1980s tycoon and investor. In an anecdote about a shipping company Icahn had bought, Icahn reportedly decided to fire the people on 12 floors of an office building because he could not work out what they did. Months later, Parr says, Icahn asked his team whether their absence had caused problems. According to the story as Parr tells it, it had not. The point is not that every business should make the same cuts; it is the posture of treating the evidence as decisive, rather than letting sympathy for existing jobs settle the question.
Complex deals can look simple from the inside
Parr’s third trait is comfort with complexity. He says natural money-makers can grasp deals with multiple contingencies and compare them quickly against alternatives. Many people prefer to keep business simple; these founders are willing to work through tangled situations, including ones involving compounding, asset purchases, or operational changes. Parr says he has noticed that they tend to have high IQs and can see where value is locked up in a complicated deal.
Puri partly disputes the description. The natural money-makers he knows, he says, often prize simplicity. They may see a complicated undertaking as straightforward—not because there is nothing difficult about it, but because they have found a simple reason to do it and a practical path through the execution. The complexity may be apparent to an outsider, while the person doing the deal sees a short chain of questions that can be answered.
He describes an unnamed founder who ran a consumer-products business and responded to rising production costs by building a manufacturing plant. The founder visited a European manufacturer, asked what the equipment cost and how quickly it would pay back, then found out who could supply it and persuaded people with experience to help install it in the United States. Puri says the plant was operating about a year later and the company’s cost of goods fell by half. He would have shied away from the project as unfamiliar and complicated. The founder’s reasoning, by contrast, was concise: if the payback worked, find the people and equipment needed to make it happen.
That distinction—simple reason, difficult execution—is also how Puri revises his understanding of Syed Balkhi’s gas-station investments. Parr describes Balkhi as a particularly clear example of the natural money-maker: he began with a WordPress blog, used its profits and influence to buy WordPress plugins, and went on to invest in real estate, stocks, and private companies. Parr had questioned why Balkhi would buy relatively small gas stations when he was already worth hundreds of millions. Balkhi’s answer, as Parr recalls it, was that the returns were good and the process made sense.
Puri says Balkhi explained the investment in simple terms: find a hard corner in a good area and look at the track record. Balkhi also described using a triple-net lease. Puri says he had initially balked at the unfamiliarity and the prospect of managing the investment; Balkhi presented the arrangement as simple. Puri suggests that people often confuse unfamiliarity with complexity and uncertainty with risk. The natural money-maker may be more willing to investigate the unknown, then reduce it to the few facts that determine whether to proceed.
Puri also recalls Balkhi’s advice on spending: “only spend the second derivative.” In practical terms, as Puri explains it, the idea is not to spend the original income or principal, but to invest it and spend only the returns produced by those investments. Someone who earns $100,000 might invest it and treat the resulting gains as the discretionary pool, rather than immediately upgrading their lifestyle. As the invested amount compounds, that pool can grow.
Parr describes his own rule in similar terms: keep his annual budget below 3% of liquid net worth, so that he can feel confident the money will not run out. He calls it “don’t touch the principal; only live off of the interest,” while noting that “interest” is not quite the right word. Puri sees the approaches as versions of the same principle: preserve the underlying assets rather than consume them as income rises.
Making money is not the same as living well
Parr pushes back on the assumption that this approach necessarily produces a miserly or unhappy person. He says he knows natural money-makers who are happy, generous, and good to their families, as well as others who are miserable and difficult. He sees no reason to assume the archetype determines a person’s character or quality of life. To make the point, he recalls people telling Bryan Johnson to loosen up and eat birthday cake; Johnson’s response, Parr says, was that he was happy living as he did.
Puri agrees that dismissing careful financial habits as joyless can be a defensive reaction. Someone who feels guilty about not being as disciplined may decide that the disciplined person is simply having no fun. A more useful response, he says, is to ask how the approach works, then decide whether any part of it is worth borrowing.
But Puri also names a cost that can accompany being good at business. People who love the game, gain status from it, and get a strong feedback loop from winning can keep trading time for more money after money has stopped improving their lives. He calls this “trading valuable hours for useless dollars”: accumulating wealth that someone may never need or spend, while telling themselves it is for their children or that their children need to see them work hard. Puri’s point is not that ambition is inherently a problem, but that additional money may stop improving someone’s daily life while the hours spent earning it remain valuable.
The same avoidance can show up outside money. Puri says it is easier for him to read another article or make another slide deck than to go running, even though exercise may do more for his quality of life. He makes a similar point about marriage: it can be more valuable to show up differently and bring more energy to the relationship than to add another amount to a portfolio that is already just a number on a chart. Those changes can be hard precisely because they require leaving a familiar area of competence and entering one where progress is less obvious.
Puri gives learning piano as an example from his own life. He chose to spend time on something he was bad at, would not earn money from, and was unlikely to be praised for. He did it because making music and learning a skill brought a different kind of enjoyment. For him, the relevant choice is not whether to make more money or reject ambition. It is whether to keep putting time into the activity with the clearest reward, or to invest in parts of life where the payoff is less familiar.
The source of the instinct remains unsettled
When Puri asks whether natural money-making is nature or nurture, Parr does not settle on one explanation. He thinks these people are often raised in families where business and money are discussed at a young age, and he also says the disposition may be something they are born with. Separately, he points to a competitive streak—a desire to conquer or win that can appear from a young age, especially around making money. He does not claim to know why it develops, and leaves open how much comes from upbringing, temperament, or some combination.
Parr invokes Napoleon’s line about being descended from conquerors to capture the attitude. Intelligence may be part of the picture, he suggests, but so is simply wanting to win. Syed Balkhi is one example Parr offers. Balkhi began with a WordPress blog, used the profits and influence to buy WordPress plugins, and later invested in gas stations, real estate, stocks, and privately held companies. Parr says Balkhi is willing to pursue returns that seem too small or complicated to other people.
Founder archetypes are different ways to win
The natural money-maker is only one possible play style, and the three traits Parr names are not a complete taxonomy of founders. The hosts explore other labels as possibilities, not fixed or mutually exclusive categories. Parr says Jesse Itzler, whom both hosts admire, does not fit the natural money-maker type. He describes Itzler instead as an “extreme balancer”: someone who is intensely deliberate about taking vacations and pursuing adventures, and who commits fully to those experiences. Parr also offers Brian Chesky as a missionary, a founder whose life is organized around a mission he believes in—in Chesky’s case, building Airbnb and making travel good.
Puri proposes a “tank”: an operator with relentless forward energy, high pain tolerance, and the capacity to lead a large organization through sustained effort. He associates this type with Frank Slootman, describing the archetype as tactical and militant: a leader who can absorb resistance and keep an organization moving.
At the opposite end of the metaphor is the “trickster.” Puri means the name as a compliment, not an insult: these people have a kind of magic for turning an overlooked object or idea into a product people want. He cites Alex Tew, who made the Million Dollar Homepage and later Calm, whose early product was an app that invited users to do nothing for two minutes. He also mentions a business built around letting customers name a star, and Parr places Eric Ryan—who started Method Soap, Olly vitamins, and Welly bandages—in this category.
Puri adds the “fierce nerd,” drawing on Paul Graham’s writing about highly competitive people who can seem quiet in ordinary social settings but are formidable in the competitions they care about. He uses Mark Zuckerberg as an example of the dynamic: being socially awkward or nerdy does not mean being weak; it may mean the person is fierce on a different battlefield. Parr puts Travis Kalanick in a related category, as someone who treats business as a game and enjoys playing aggressively.
There are also what Puri calls “deep students”: people who do not necessarily play a particular game themselves but study its history with unusual endurance and depth. He points to Dan Carlin and David Senra as examples of people fascinated by the decisions and lives of those who played the game before them.
Finally, Puri distinguishes the “sniffer” from the natural money-maker, while noting that the categories are still being worked out. Both notice opportunities, but the sniffer, in Puri’s formulation, is more oriented toward spotting and investing in them than being hands-on in the business. Puri says Austin Rief, whom he identifies as being from Morning Brew, has repeatedly pointed him toward non-obvious people, categories, and trends that later proved significant. He also recalls a friend, Vishal, encouraging early investments in Bitcoin and later identifying stablecoins, privacy coins, and prediction markets as areas to watch. Puri says he did not always recognize the significance at the time.
Parr says sniffers tend to be enthusiasts as well as businesspeople: they get excited and want to share what they see. Natural money-makers, by contrast, may keep quiet about a deal. The distinction is a tendency, not a hard boundary. Puri names Sean Parker as a prominent example of a sniffer, citing his recognition of Napster and Facebook, and his early enthusiasm for Spotify. In a message to Spotify’s founders, Parker praised the product’s experience and described having dreamed since Napster of building something similar. The advantage, as Puri describes it, is a “conviction arbitrage”: believing in a person or opportunity before others do, and acting on that judgment.
The labels remain exploratory. The hosts try out missionary, extreme balancer, tank, trickster, fierce nerd, deep student, and sniffer, while acknowledging that some names need work. They do not present the list as exhaustive, or as a system that assigns each person to only one type. The point is not to sort every founder neatly, or to rank one play style above the rest. Parr says he is not envious of every natural money-maker’s life, but he is interested in the attributes they have that he lacks—and in asking what he might borrow in a particular situation.
Puri connects the exercise to a point he attributes to Ray Dalio: whether a person will have more success fighting their nature or working with it. The archetypes are a way to consider how people’s natural wiring might shape the work they are suited to, rather than a verdict on who is good at business. Parr’s broader invitation is to ask where you find yourself drifting, and what useful traits you might learn from people who play differently.